
The Connective Fabric of Natural Resource Governance: Reflections from UNGA and Climate Week

Last week, a delegation from NRGI attended the UN General Assembly and Climate Week NYC. Below are our reflections from across more than 20 sessions, side events, our 20th anniversary convening and meetings, with partners from government, civil society, Indigenous Peoples, multilaterals, philanthropy and industry.
Natural resources rarely dominate the headlines at the UN General Assembly, yet they underpin almost every item on its agenda. Whether conversations centered on climate, economic development, trade or geopolitics, the governance of oil, gas and minerals ran through many of them.
That role, however, too often remains implicit. Elevating resource governance as a priority is essential if global efforts on climate, development and security are to deliver equitable outcomes for producer countries and their citizens, and a healthy, sustainable future for all of us.
Security and trade have reframed the journey, but not the destination
Energy security has displaced energy transition as the dominant lens for energy policy, with decisions increasingly driven by geopolitics and cost of living rather than decarbonization. While the end goal of sustainable energy and economic futures remains, this marks a structural shift in the narratives that shape policy and in how influence is exercised.
In the minerals sector, a trade lens now dominates, even during a “Climate Week”. Green industrialization was a central theme, welcomed by some and viewed with skepticism by others. At a UN-hosted Solutions Dialogue on the subject, producer countries, particularly those from Africa, stressed that high costs of capital and limited fiscal space must not constrain their economic and trade ambitions. African participants were clear that the gap is now implementation, not strategy: frameworks such as the African Mining Vision and the Africa Green Minerals Strategy already exist. Because no single country holds every mineral, energy source, skill and market, enabling countries to achieve more value requires regional integration. The African Continental Free Trade Area (AfCFTA) serving as an industrial platform rather than only a trade agreement. Success, many argued, should be measured by the jobs, skills and productive capabilities retained on the continent, not by processing capacity alone. In our remarks, NRGI emphasized the need for additional financing and technical support so that producer countries can design, implement and monitor value addition and diversification strategies that truly meet the needs of their people, and enforce high human rights, environmental and governance standards.
Green industrialization could serve as a bridge that brings mineral trade and climate policy closer together. We are looking forward to further progress at COP31 in November, as green industrialization is a key priority on the Action Agenda launched by Türkiye last week. Looking to next year, NRGI is also supporting a shared agenda on equitable mineral partnerships across the COP32 and UK-led G20 processes, where African countries have an opportunity to connect their climate positions with their leverage as producers of critical minerals.
"Critical for who?": equity and the governance gap
With “critical minerals” being used so often, the question "critical for who?" recurred throughout. Across discussions, there was a unifying call for a new and more equitable economic and political paradigm, but how this plays out in practice remains highly uncertain. There were multiple calls (including from NRGI) for critical minerals to underpin just, country-led transitions that serve producer countries' development aspirations, respect the free, prior and informed consent of Indigenous Peoples and frontline communities, and remedy legacy environmental harms. Several sessions went further, asking not just how much revenue extraction generates but whether it preserves national wealth across generations. Without this, producer countries risk exchanging finite mineral wealth for limited revenues while leaving depleted assets and environmental damage to future generations.
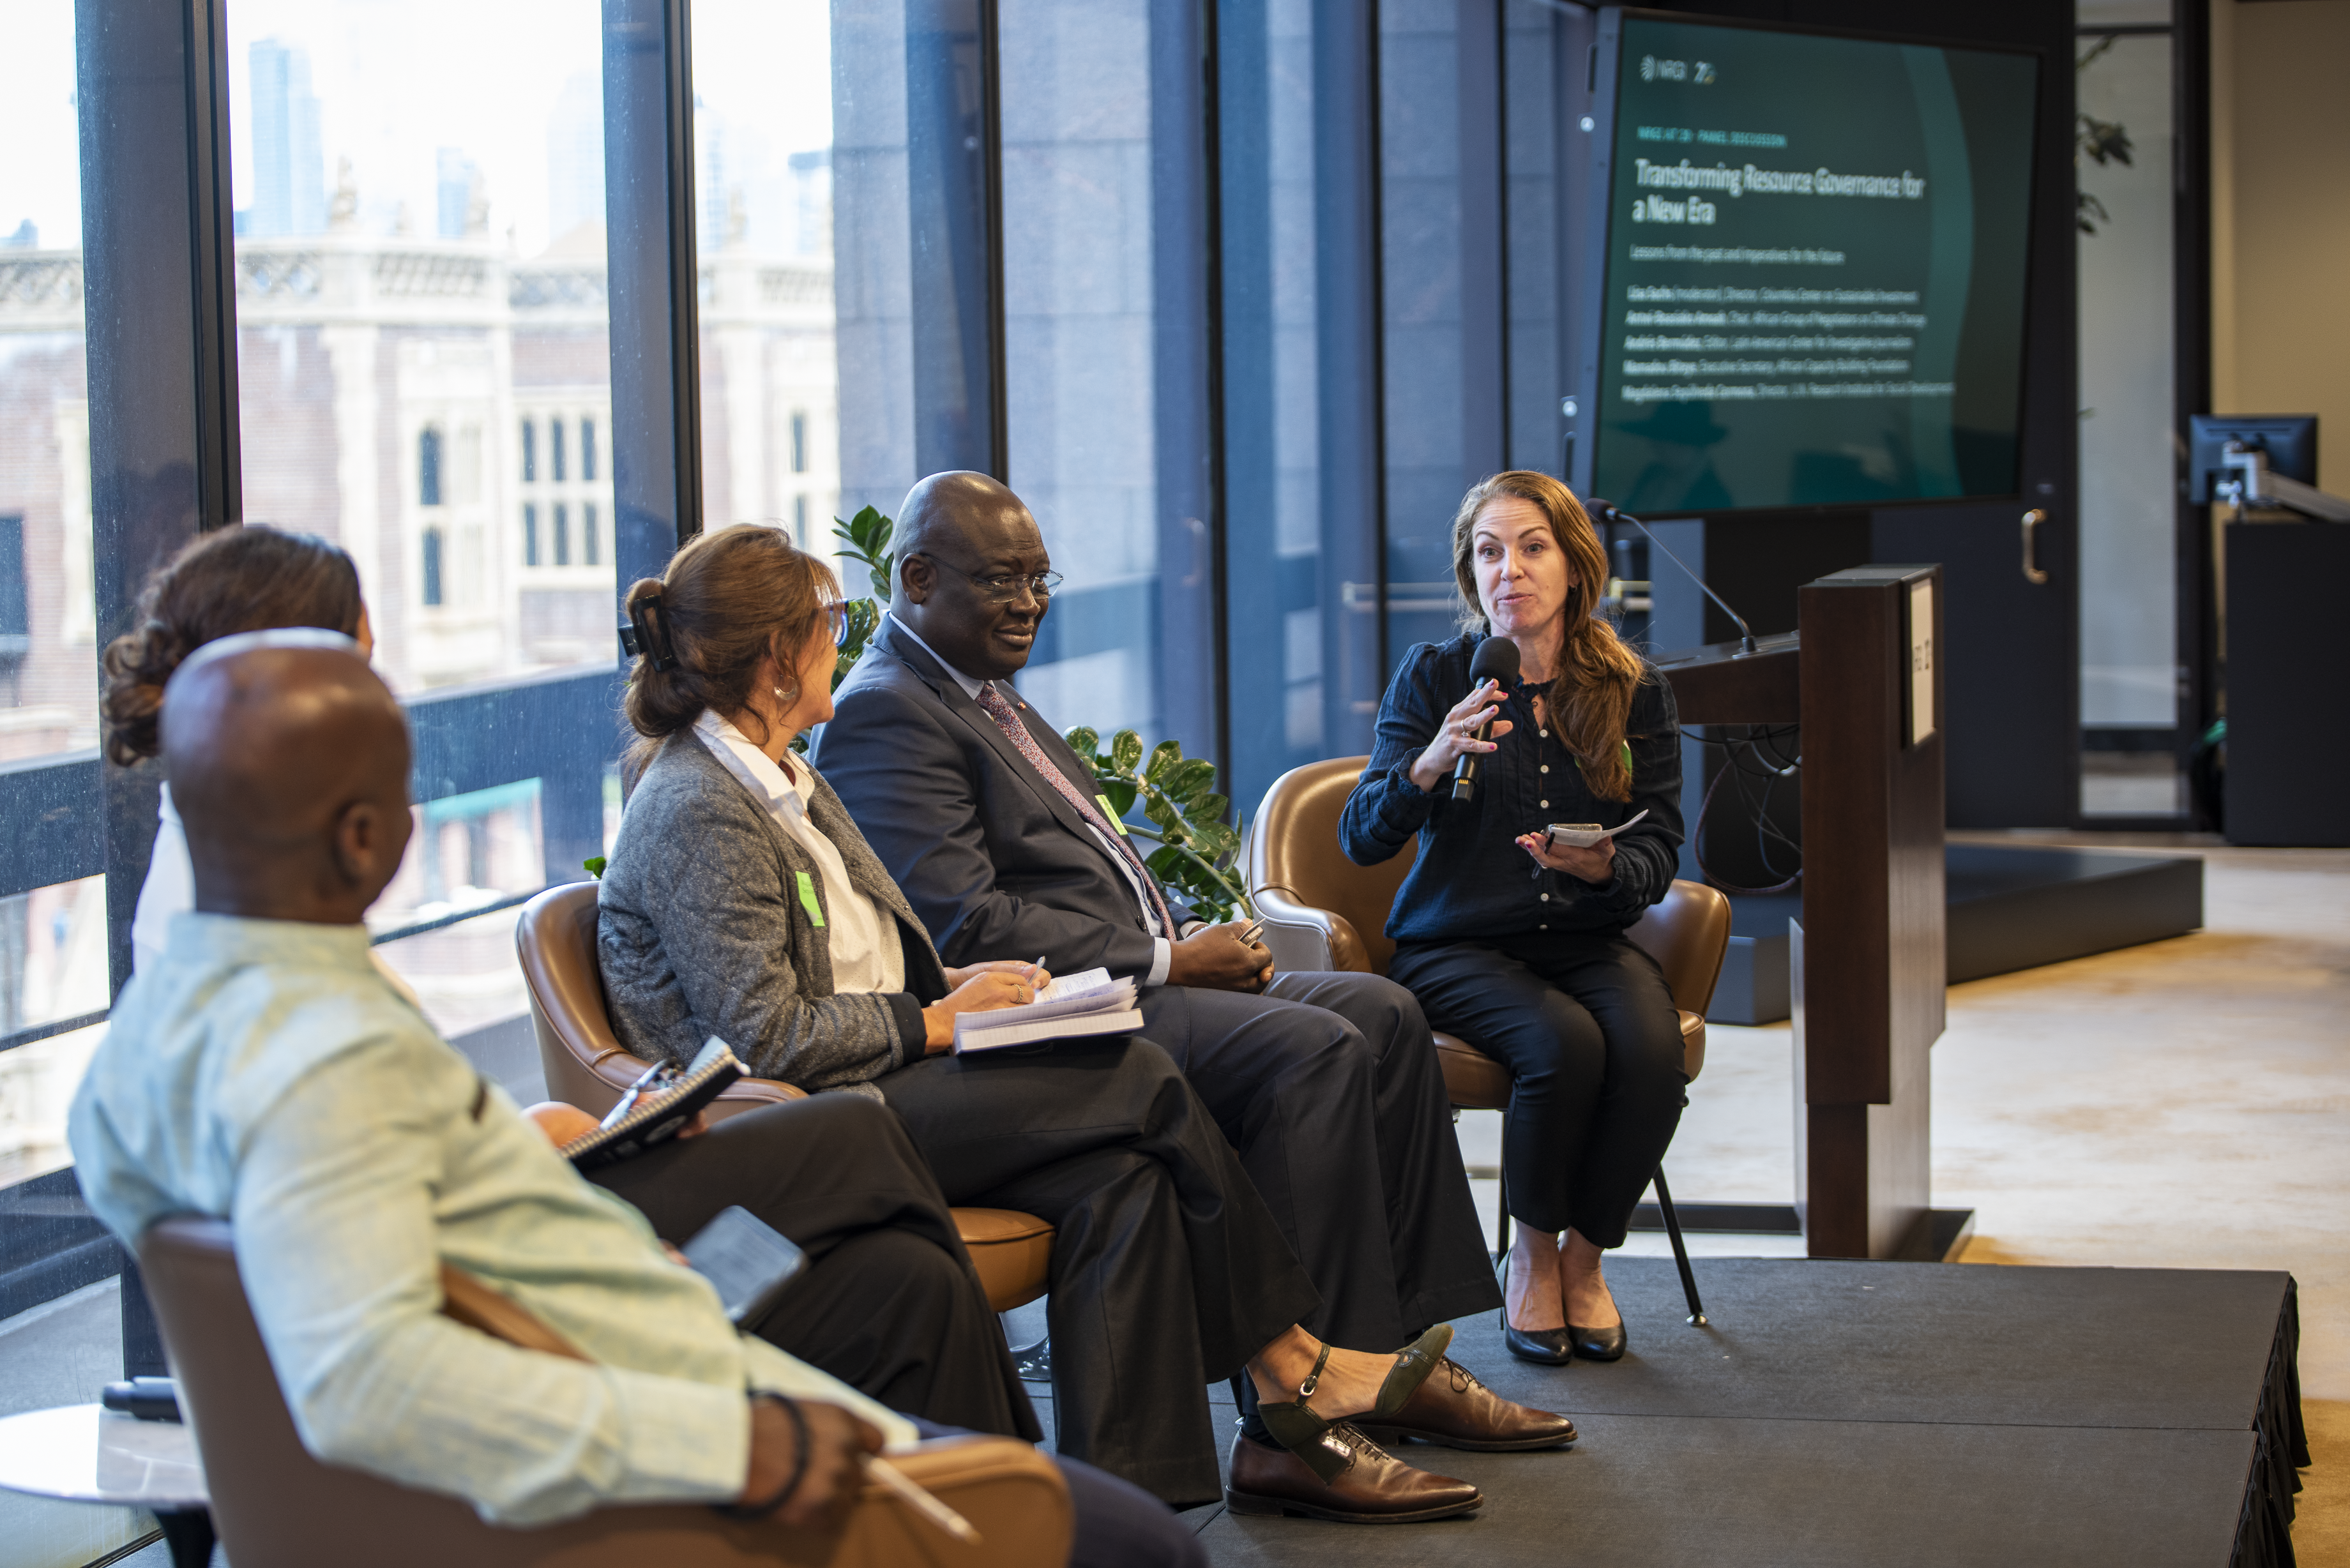
While critical minerals are the focus, the obstacles to fairer and more prosperous societies are structural and systemic – a theme that echoed throughout including in NRGI’s 20th anniversary event. Low- and middle-income countries remain underrepresented in setting new standards and paradigms, despite bearing their costs.
Encouragingly, the discussion has moved from what must change to how. Reformers shared approaches ranging from multi-stakeholder engagement and narrative storytelling to strategic litigation, the quantification of decommissioning liabilities and evidence on the financial materiality of community engagement. Each aims to ensure that community rights are respected and that polluters remediate the harm they cause. A recurring message was that affected communities need agency, not simply better consultation: access to information, the capacity to negotiate and the ability to speak for themselves with governments, companies, investors and financiers. These “unbankable” elements often determine whether supposedly bankable investments succeed.
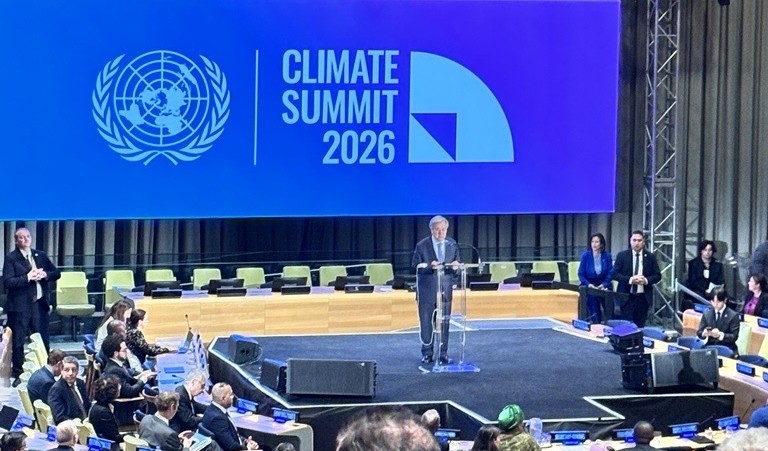
Concrete openings exist to keep making progress. At the UN Climate Summit, the Secretary-General announced a new country support mechanism for six mineral-rich developing countries to implement the recommendations of the UN Secretary-General's Panel on Critical Energy Transition Minerals. Having served on the panel, NRGI and our partners have pressed for this follow-through, including in this joint letter last July. We welcome the mechanism. Connecting with technical assistance partners outside the UN to deliver tailored, demand-led support will be critical to its success. (Learn more: See our video and press statement released during the week). The push for an International Panel on Inequality and next year’s planned SDG Summit offer further entry points to center producer countries in debates on the future economy. The ongoing review of the IFC Performance Standards is another, as these standards shape the practices of commercial banks, export-credit agencies and mining companies well beyond the IFC itself.
Artificial intelligence and the resources beneath it
Some described this as the "AI UNGA". Technology leaders addressed the Security Council, many world leaders mentioned AI in their speeches, and there were countless AI-focused side events. Yet beyond limited discussion focused on data centers, few conversations linked AI development to the minerals that build and power it. This is a gap that policymakers, companies and civil society alike must close.
A notable exception was a discussion convened by the government of the Democratic Republic of the Congo, entitled “AI and the New Geopolitics of Peace and Security”, in which NRGI participated. It followed a July Arria-formula meeting, held during the DRC's Security Council presidency, which called for a global normative framework reconciling peace, security, transparency and sustainable development. NRGI has provided technical input to that process, and this intersection is emerging as a key policy space.
The DRC's leadership is itself both noteworthy and an opportunity. It shows how low- and middle-income countries can shape emerging global norms on minerals, security and AI, rather than simply adopt rules set elsewhere.
A fragmented landscape demands trusted brokers
While emerging coalitions and new opportunities are being born of the current upheaval, fragmentation and polarization remain a challenge. Progress will depend on trusted brokers who can navigate contradictions to unite diverse groups, and on building new, action-focused coalitions.
For NRGI, we see this as a challenge and an opportunity. We will seek to leverage the trust, credibility and knowledge we have built over two decades, while holding a nuanced, independent position in a multi-polar world.
National Dialogue on Nigeria’s Energy Transition: Exploring Energy and Economic Diversification Pathways
Abuja, Nigeria

Nigeria stands at a critical point in its energy and economic development journey. Despite its vast oil, gas and renewable energy resources, the country continues to face widespread energy access challenges, unreliable power supply and deep dependence on fossil fuel revenues.
As global energy markets shift and climate commitments accelerate, Nigeria must make strategic choices about how to expand energy access, strengthen economic resilience and prepare for a future beyond oil and gas dependence. NRGI, in partnership with the National Council on Climate Change (NCCC), The Nextier Group and The Electricity Hub, will convene a national dialogue to bring together government, civil society, industry, media, experts and development partners to explore practical pathways for Nigeria’s energy future and economic diversification.
The dialogue forms part of NRGI at 20, marking two decades of the organization's work supporting governments, civil society and other stakeholders with independent research, technical expertise and evidence-based dialogue to strengthen natural resource governance and ensure that resource wealth delivers lasting public benefit.
Objectives
The dialogue aims to:
- Sustain national conversation on Nigeria’s energy transition.
- Identify practical pathways for energy and economic diversification.
- Build consensus among stakeholders on credible transition options.
- Explore governance reforms needed to support a successful transition, including transparency, accountability, revenue management, public participation, local content and institutional coordination.
- Generate actionable recommendations for the governments on managing the economic and fiscal implications of the energy transition.
Expected Outcomes
The dialogue will produce:
- A stronger shared understanding of Nigeria’s energy transition choices and diversification opportunities.
- Consensus on pathways to decarbonize Nigeria’s energy systems and strengthen economic resilience.
- A post-dialogue communique or outcome report capturing key messages and policy recommendations.
Speakers
- Tenioye Majekodunmi, Director General, National Council on Climate Change (NCCC)
- Mustapha Abdullahi, Director General, Energy Commission of Nigeria (ECN)
- Iniobong Abiola-Awe, Director, Department of Climate Change, Federal Ministry of Environment
- Abba Abubakar Aliyu, Managing Director / CEO, Rural Electrification Agency (REA)
- Ibrahima Aidara, Deputy Africa Director, NRGI
- Jonathan Gaza, Chairman, House of Representatives Committee on Solid Minerals, National Assembly
- Tengi George-Ikoli, Nigeria Country Manager, NRGI
- Ibrahim Shelleng, Senior Special Assistant to the President on Climate Finance and Stakeholder Engagement, Office of the President
- Emeka Okpukpara, Partner, Nextier
Featuring NRGI's

Tengi George-Ikoli
Nigeria Country Manager
Ibrahima Aidara
Deputy Africa Director
Aaron Sayne
Lead, Sustainable Energy Supply
Ahmad Abdulsamad
Nigeria Program Officer
Damilare Ogunmowo
Africa Communications Officer
One Crisis, Seven Lenses : MENA’s Energy Transition at a Crossroads
What the 2026 energy shock means for the future of transition in MENA

In early 2026, the U.S.-Iran war and the closure of the Strait of Hormuz triggered the most severe energy supply shock in decades — disrupting global hydrocarbon flows and exposing just how fragile and interconnected energy markets are. In the Middle East and North Africa (MENA), the shock carried different meaning for fossil fuel producers trapped by the Hormuz closure, for other fossil fuel exporters, and for energy-importing countries. But for every government in the region, it landed on territory where energy is already a daily household concern, and where the transition to cleaner, fairer energy was only beginning to gain momentum.
The crisis pushed energy security to the top of every policy agenda in the region, while simultaneously raising new questions about the future of the transition itself. The same shock is pulling policymakers, investors, and communities in multiple directions at once. Which path prevails will depend on the choices made now.
That is why we set up the NRGI MENA Just Energy Transition Platform, as a space for knowledge production, dialogue, and advocacy among those committed to a transition that is not only faster but fairer, anchored in strong governance foundations. Among the community of experts, we work with an Advisory Expert Group to support and guide us — leading voices on energy, governance, and transition from across the region. In the weeks following the crisis, we put one question to this group: What does this moment mean for the future of energy transition in MENA? Each responded from a different vantage point. Read together, they converge on the same central tension.
The reflections below are short excerpts from longer contributions by members of the NRGI MENA Just Energy Transition Platform Advisory Expert Group. You can read their full analyses in the briefing available for download at the end of this page.
The Strategist's Lens — Dr. Manal Shehabi — Senior Research Fellow, University of Oxford; NRGI MENA Advisory Board
The crisis cuts both ways for MENA's energy transition. Gulf exporters, unable to reap their usual windfalls, are cutting long-term transition spending first. Oil importers like Jordan, Egypt and Morocco have the strongest incentive to accelerate — but the least fiscal room to do so. The same shock that makes the transition more urgent is also what makes it hardest to fund.
The Resilience Lens — Dr. Mohammed Al-Breiki — Head of Industrial Studies and Policies, Gulf Organization for Industrial Consulting (GOIC)
For the Gulf, the crisis is not a choice between hydrocarbons and transition — it is a push to manage both. Higher revenues are being directed toward resilience, economic diversification and deeper regional integration: energy grids, the GCC railway, strategic reserves. Hydrocarbons remain the source of stability while the longer-term shift is built.
The Trade-offs Lens — Sarine Karajerjian — Program Director, Environmental Politics Program, Arab Reform Initiative
The crisis forces fragile MENA governments to navigate five trade-offs at once: security vs. transition, centralized vs. decentralized power, fiscal stability vs. social protection, speed vs. governance, and diversification vs. geopolitical alignment. How they balance these competing pressures — not whether they transition — will decide whether the shift is fair or deepens existing inequalities.
The Gender Lens — Myriam Sfeir — Executive Director, Arab Institute for Women
The energy crisis hits women hardest: more unpaid work, less income, and deeper inequality. Yet policy continues to treat all households alike. Effective responses require gender-sensitive energy policy that sees who is actually absorbing the cost — and designs support accordingly.
The Civil Society Lens — Dr. Pierre Saade — Head of Middle East and North Africa, Resource Justice Network
Civil society's role is to bring big energy decisions back down to lived reality — the cost of cooking, transport, and electricity — and to ask who benefits and who bears the risk as pipelines and corridors return under the banner of energy security. As energy access grows more conditional and contested, democratic oversight and community accountability matter more than ever.
The Opportunity Lens — Dr. Jauad El Kharaz — Co-Chair, Mediterranean Clean Energy Network (MEDCEN)
What if the crisis is the opening, not the setback? A Mediterranean remade not as a fossil gas corridor, but as a global green energy hub — 1 TW of renewables by 2030, powering local industry, not just exporting to Europe. The political and financial momentum created by this crisis may be exactly what makes that ambition achievable.
The Media Lens — Roula Mikhael — Executive Director, Maharat Foundation
Media coverage of the crisis stays fixed on prices and shortages, missing the bigger story of structural transition — held back by limited access to energy data and varied editorial pressures across the region. Stronger technical expertise among journalists and a more constructive journalism approach could shift coverage from reactive reporting toward informed, accountable, and forward-looking public debate.
Seven lenses. One crisis. One central tension: whether the energy transition can survive a shock that makes it both more necessary and harder to fund.
The energy transition has become an energy-security argument, not only a climate one. The resilient path runs through renewables, grids, and decentralized systems — but it only holds if the people bearing the cost stay at the center, and the governance of fast deployment keeps pace with ambition. That is what the NRGI MENA Just Energy Transition Platform exists to ensure.
Read all seven perspectives in full — download the briefing: One Crisis, Seven Lenses
Beyond Oil and Gas: Regional Perspectives on a Transition Under Pressure

As more than 50 countries gather in Santa Marta for the first conference dedicated to transitioning away from fossil fuels, NRGI's regional directors share how governments are navigating competing pressures, and what this means for economies and communities
The energy transition is happening. It is also, depending on your perspective, too slow, too fast, too expensive, or something else entirely. As the governments of Colombia and The Netherlands convene the first-ever conference dedicated to transitioning away from fossil fuels in Santa Marta, that ambition is running up against a charged reality: oil price spike, land grabs, geopolitical jockeying for resources and mounting debt in many producer countries.

NRGI’s work is grounded in the recognition that how the transition unfolds—and how quickly—will determine whether it contributes to fair, inclusive and more prosperous societies, while acknowledging that communities that have contributed least to the climate crisis too often stand to lose the most. There is not one transition. There are transitions—shaped by very different starting points, economic realities and development priorities. Those gathering in Santa Marta must consider these diverse perspectives, including from communities, countries and regions that are not always fully represented in these debates.
Three of our regional directors reflect on how the transition is unfolding in practice, drawing on two decades of work on resource governance.
How are governments approaching the transition in the current context?
Santa Marta's organizers argue that current conflicts reinforce rather than sideline the case for transition. For governments navigating oil price uncertainty, rising energy demand and immediate security pressures, however, the picture is more complicated.
Africa—Nafi Quarshie, Africa Director

Latin America—Ana Carolina González Espinosa, Latin America Director and Senior Director for Programs

MENA—Laury Haytayan, MENA Director


The Price of Instability: Oil Shocks, Energy Transitions and MENA's Economic Future

The ongoing conflict in Iran, Lebanon and across the region is devastating lives and livelihoods, and driving significant uncertainty across the Middle East and North Africa (MENA). While much remains unclear, it is certain there will be far-reaching implications for economic stability, energy markets and policy trajectories—particularly in the Gulf Cooperation Council (GCC) countries and Iraq.
While much attention has focused on immediate effects, less explored are the medium- to long-term structural impacts on regional economies and energy strategies.
This webinar brings together leading experts from the worlds of business, politics and civil society to examine the "price of instability"—how the conflict may reshape oil and gas markets, fiscal stability, investment patterns and energy transition pathways across MENA. It will also explore how governments, especially in the GCC and Iraq, may adapt their policies in response to evolving risks and opportunities.
The discussion will combine energy market analysis, macroeconomic perspectives and geopolitical insights to provide a forward-looking view of the region’s resilience and strategic choices in a more volatile environment.
Speakers:
- Carole Nakhle, CEO, Crystol Energy
- Rola Dashti, Kuwaiti economist and senior public leader
- Lina Khatib, Associate Fellow, Chatham House
Moderator:
- Laury Haytayan, Regional Director, Natural Resource Governance Institute
This webinar will be conducted in Arabic with simultaneous English interpretation.
Gas in Mexico: Risks and Alternatives for a Sustainable Energy Model

Key Messages
- Mexico is critically dependent on imported gas for its energy system.
- More than 70 % of the gas consumed nationally comes from the United States, primarily through pipelines from Texas, creating vulnerabilities and exposing Mexico to significant risks.
- For years, energy policy has been based on three assumptions that require urgent review: 1) that Mexico will have sustained access to an abundant and reliable gas supply; 2) that U.S. gas prices will remain low and stable; and 3) that gas use does not compromise Mexico’s climate and energy transition goals.
- In an increasingly dynamic and uncertain context, growing dependence on gas—especially imported gas—increases the country’s exposure to emerging risks such as potential supply disruptions, price volatility, geopolitical realignments, rising methane emissions, and possible stranded assets.
- Without strategic management of these risks, the consequences for Mexico’s energy security and sustainability could be severe. It is urgent to analyze these risks and assess whether the current gas strategy is compatible with the country’s energy transition and climate objectives.
- This document offers a realistic perspective that acknowledges gas’ contributions but also identifies limits and conditions for its future use, proposing key questions to guide the debate.
The growing Mexican dependence on gas, particularly that originating from the United States, today represents one of the most pressing challenges to the country’s energy security.
Gas supplies most of the electricity generation and is an essential input for industry and Pemex. This centrality has been built on a growing dependence on imports from the United States. The deepening of this dependence has exacerbated the country’s energy vulnerabilities, making it more susceptible to adverse conditions.
This discussion paper examines the assumptions that have guided energy policy around gas in light of emerging risks in an increasingly dynamic and uncertain context. The risks identified are grouped into three main categories: supply risks, economic risks, and environmental and climate risks.
This analysis seeks to contribute to a more informed and realistic debate on the role of gas in Mexico, helping to move beyond the polarized positions that currently prevail. It offers a pragmatic, evidence-based approach that recognizes the complexities of today’s energy system while also identifying the limits and conditions for the future use of gas.
To advance in this direction, four key priorities are identified:
- Adopt a comprehensive risk assessment framework for gas.
- Advance an orderly and coherent energy transition that harmonizes the role of gas with renewable energies
- Develop a gas demand management policy.
- Strengthen capacities for measuring, monitoring, reporting, and verifying methane emissions.
Mexico has the legal framework, technical capacities, and institutional tools necessary to reduce its structural dependence on gas and mitigate the risks that derive from it. Strategically leveraging these capacities will be essential to ensure a reliable, affordable, and sustainable energy supply in the coming decades.
From Kyiv to Kinshasa: Five Lessons for Governments Navigating Mineral-for-Security Deals

As the ink was drying on the recent Ukraine-United States agreement, questions quickly arose: could this approach, which puts mineral resources at the heart of security diplomacy, serve as a model for mineral producing countries in Africa and beyond? Today’s announcement of a U.S.-brokered agreement around the conflict in the Democratic Republic of the Congo (DRC) with Rwandan-backed rebels raises the possibility of a frequently mentioned linked U.S. minerals deal being a next step, making it timely to consider implications of the Ukraine deal elsewhere.
With the Trump administration having set the tone by aggressively linking U.S. diplomacy to commercial and geopolitical mineral competition, a wave of state-to-state mining agreements may well be coming—with some focused on the minerals-security nexus.
Some governments and stakeholders in mineral-producing countries may view these new deals with trepidation, not least given the intense diplomatic pressure pushing them to the negotiating table, the role minerals have long played in conflicts and some negative experiences with somewhat analogous resource-for-infrastructure deals in past decades. Others may welcome a novel structure to support their broader security or development ambitions. Regardless of their orientation, lessons from Ukraine's newly signed deal and earlier African country experiences can help governments navigate this environment of deal-making in the pressure cooker of the current geopolitical moment.
Choices made by Ukraine and other countries in the context of war and an urgent need for international support should be understood accordingly. Still, governments have important lessons to draw upon, including around the importance of transparency, the need to look beyond rhetoric to the concrete lasting obligations, the challenges of valuing mineral resources and what’s received in return, and how to advance long-term objectives while prioritizing short-term security needs.
Transparency is essential
The frequent lack of public information about state-to-state mineral partnerships often makes them difficult to scrutinize. As with mining contracts generally, transparency—including around the parties involved and responsible for implementation—is essential to building public trust, deterring corruption and helping ensure fair returns to a country’s citizens.
In this sense, it is noteworthy that one of the main agreements constituting the Ukraine-U.S. deal was published by the Ukrainian government (though not simultaneously by the U.S. government) and approved by the Ukrainian legislature. This publication at least allows stakeholders to probe some of the details around two main features of the deal, namely (i) a joint investment fund for the reconstruction of Ukraine using, in part, Ukrainian government resource revenues, and (ii) commitments by the Ukrainian government to the U.S. regarding investment opportunities and offtake rights in future resource projects in Ukraine.

However, some key terms—namely those detailing contributions and withdrawals from the fund, are not set out in the published agreement, but in a separate “LP agreement,” reportedly signed weeks later, which has not been disclosed. Without transparency of the full deal documentation, stakeholders cannot have a full understanding of the deal.
African experience with resource-backed loans or resource-for-infrastructure arrangements reinforces the importance of transparency. Like today’s mineral-security deals, those deals involved mineral-producing countries using their natural resources to achieve largely unrelated benefits (e.g., financing for infrastructure in exchange for future natural resources) and often involved a global power government. For example, transparency concerns have plagued multiple stages of the DRC-China Sicomines deal, from the initial agreement to a 2017 amendment, the latest 2024 renegotiation and its ongoing implementation.
Civil society organizations in the DRC have raised concerns that a potential U.S. mineral deal risks repeating the opacity that characterized the Sicomines deal. The fact that the Congolese public apparently first learned of the potential deal with the U.S. through American media rather than their own government underscores this concern. On the other hand, the DRC government has recently published the names of the team coordinating the U.S. negotiations, aiming to reinforce public trust and preempt potential corruption concerns. The government should continue to prioritize transparency, particularly in any next step economic negotiations, allowing the public to have a better understanding of the DRC's expectations in this process.
Rhetoric doesn’t always match reality…
Transparency is important in part because with complex arrangements such as mineral partnership agreements, the devil is in the details. In negotiating or evaluating a deal, producer-country governments and stakeholders —such as civil society and parliamentarians— must look beyond the rhetoric to understand the actual terms and lasting obligations.
For example, media coverage of the Ukraine-U.S. agreement, has focused on U.S. preferential access to Ukrainian minerals and Ukraine avoiding an obligation to repay earlier U.S. for earlier military assistance. But in each of these cases, the actual terms of the agreement provide less certainty than the political rhetoric suggests.

On U.S. access to Ukrainian minerals, the White House fact sheet suggests that future natural resource projects in Ukraine are there for the U.S.’s taking: “If the United States decides to acquire these resources for ourselves, we will (sic) given first choice to either acquire them or designate the purchaser of our choice.” In practice, Ukraine achieved agreement terms that are more nuanced, clarifying that any preferential offtake terms apply only to certain resource projects and would need to be negotiated based on “market-based commercial terms.” And while the agreement mentions “certain restrictions” on offtake by others (to be detailed in the LP Agreement), the published agreement does not mention a U.S. right to designate a purchaser.
On Ukraine not repaying the U.S., this is, strictly speaking, accurate and an improvement for Ukraine from earlier Trump administration positions. However, the only specified financial commitment from either party in the published agreement is Ukraine contributing “Ukraine Agreed Revenues” (i.e., 50 percent of royalties, fees, etc. from certain resource projects) into a fund reported jointly and equally owned by the Ukraine and the U.S.. And while some sources reference the US also making financial contributions into the fund, the published agreement includes no such commitment.
Furthermore, mention in the published agreement of future military assistance counting as an “increase” in the U.S. contribution could be interpreted (unless otherwise addressed in the LP agreement) as the U.S. having already contributed to the fund. In such an interpretation, the agreement’s provisions could be viewed as a sort of conversion of “debt” (for prior U.S. military support) into “equity” for the US in the fund. Nevertheless, the narrative that Ukraine owes no repayment to the U.S. has prevailed. Ultimately the real balance seems to depend on (i) the eventual significance of the “Ukraine Agreed Revenues” and (ii) the eventual rules around withdrawal of money from the fund and any further commitments to contribute into the fund, which were to be set out in the separate undisclosed LP Agreement.
…but perceptions matter too
While analyzing deal terms is essential, the Ukraine experience shows that it is not only hard contractual obligations that matter. Even if the deal is, as some commentators have noted, unlikely to lead to significant resources or revenues changing hands anytime soon, signing it does appear to have contributed to changing the dynamic between the U.S. and Ukraine.
It has relieved pressure on Ukraine from the Trump administration and opened the door to further U.S. diplomatic support, putting the possibility of additional US military assistance back on the table for the first time under this administration. In that sense, the deal has perhaps already helped Ukraine achieve some of its short-term objectives with a U.S. administration eager to tout “deals,” even if future U.S.-Ukraine relations remain uncertain in a volatile geopolitical context. As African governments weigh the pros and cons of similar deals, these relationship considerations will certainly be a factor driving decision amidst imperfect choices.
More broadly, the Ukraine deal shows that even in power imbalances, it is possible to improve terms through negotiations. Ukrainian officials were able to at least partly resist pressure and improve the deal terms from the earlier White House proposals with apparently significantly worse terms for Ukraine, though this also depends on the terms of the undisclosed LP agreement.
Governments need to rigorously assess the value of mineral resources and what is offered in return
Fairly valuing mineral resources is always challenging in mining deals due to uncertainty around geology, prices and costs. For the Ukraine agreement, estimating the value of the “Ukraine Agreed Revenues” comes with its own challenges, but using data from Ukraine’s EITI reports on previous government resource revenues and various scenarios on the value of Ukraine’s mineral resources, while not foolproof, could help.
The valuation challenge is even greater in mineral-for-security or resource-for-infrastructure deals when assessing what is received in return for minerals. For example, the Sicomines deal has been criticized for trading significant mineral wealth for inadequate roads and poor equipment.
Security deals add further complexity because military and diplomatic assistance are often opaque and harder to value. The valuation needs to also account for the impact of such assistance. For example, while a deal between Kinshasa, Kigali and Washington could potentially address the conflict with the Rwandan-backed M23 rebels, valuing that security assistance and its impact on human rights and the economy, including on the mining sector—is difficult given there are more than 140 armed groups active in Eastern Congo.
In mineral security arrangements, a key potential benefit for producer countries, be it Ukraine or DRC, is the promotion of future resource-sector investment. But in practice achieving this often goes well beyond what is covered in the agreement. For example in Ukraine, the significant private sector investment required is unlikely until the conflict ends, especially as an estimated half of the country’s mineral wealth is currently under Russian occupation.
In the DRC, besides the security context, other challenges hindering Western mining investment include: lack of sufficient energy and transport infrastructure, a difficult business environment and Chinese market dominance. Many known deposits have already been ceded to foreign companies, limiting the DRC government’s options. Also, lack of certified geological data in certain areas, notably in rebel-controlled areas, further complicate valuation.

Short term security needs will understandably be prioritized, but impacts on long term objectives should also be considered
Immediate peace and security considerations understandably carry overwhelming weight in political decision-making for countries suffering an armed conflict. For countries such as Ukraine and the DRC, negotiating from unstable positions, strategic concessions may be rational trade-offs for stability.
At the same time, Ukraine’s experience shows other prospective deal-making governments that even in such a context, governments can also guard against undermining long-term objectives. For example, Ukraine’s negotiating team was clearly aware of the risk that the deal terms could undermine Ukraine’s ambitions around EU accession by falling afoul of EU market access requirements. President Zelensky also made clear that he would refuse “to sign something that ten generations of Ukrainians will be paying for.”
In considering long-term implications, governments should consider the duration of any deal and the ability of parties to terminate is important. The published Ukraine-U.S. agreement only terminates upon mutual agreement, meaning provisions such as Ukraine’s revenue contributions and U.S. preferential offtake rights could, in theory, be meant to continue in perpetuity. Combined with provisions that the agreement prevails over Ukrainian law and benefits from legal stabilization, this indefinite duration raises questions around the sustainability of the deal, particularly if a dispute arises around how fund revenues are used.
The Agyapa deal considered by the Ghanaian government in 2020 raised some similar issues: it proposed assigning a significant part of future government gold royalties in exchange for an upfront payment, but the lack of clarity around the value of royalties being assigned and the indeterminate duration of the arrangement raised concerns, contributing to the deal not moving forward.
Deals negotiated amid conflict are subject to different dynamics and will be judged largely on their success in resolving security crisis. Even so, producer-country governments should factor their long-term goals. For Ukraine, this includes EU membership; for the DRC, broader goals beyond immediate security may also include improved mineral exploration, technology transfer and value addition.
Many mineral-producing countries such as the DRC are looking to move beyond extraction toward mineral value addition supporting industrialization. The DRC has concluded agreements in recent years to diversify commercial partners in the mining sector and increase local value. These include cooperation agreements with Zambia on electric vehicle battery value chains, as well as with the EU, Saudi Arabia, China and Japan, and with various state-owned and private companies.

Any eventual DRC-US agreement may therefore also be judged by Congolese stakeholders partly on whether it supports or undermines these ambitions. This is complicated by the possibility that a DRC-U.S. deal could involve Rwanda. One report suggests an eventual deal could involve “the creation of an industrial zone in Congo that would export processed metals via its neighbors,” while others indicate that Kigali sees negotiations “as an opportunity to legitimize access to Congolese resources and attract investment to expand its own existing metals processing.” The latter outcome could face criticism that negotiations prioritize short-term political survival of the governing coalition over the country’s long-term development goals.
Conclusion
The new context of state-to-state mining agreements may reshape what a “good deal” means for mineral-producing counties. As the DRC and others consider such arrangements—especially minerals-for-security deals—lessons from Ukraine and earlier resource-for-infrastructure deals can offer valuable guidance.
Given the polarized geopolitical context in which these deals are being negotiated, producer countries can benefit from maintaining strategic neutrality as much as possible. This is important for countries like the DRC to safeguard sovereignty and retain control over policy- making and the national development trajectory.
Ultimately, any deal will be judged on its implementation and impact. Transparent and measurable implementation will be essential to ensure benefits reach the population.
The Energy Dilemma: Energy Transition and Regional Collaboration in the Middle East and North Africa

Key messages:
- The Middle East and North Africa (MENA) region has abundant hydrocarbon reserves as well as vast renewable energy potential, giving it a unique and profitable position in the global energy transition.
- Governments in the MENA region are strategically leveraging hydrocarbons and renewables to reduce emissions and enhance energy security.
- Cooperation between MENA countries is crucial to building an integrated energy infrastructure, boosting competitiveness, and facilitating access to global markets.
- Engaging the private sector will be vital for advancing MENA’s energy transition. Governments must incentivize participation through partnerships, supportive policies and favorable investment conditions.
- Strategic policies–such as developing integrated energy infrastructure, fostering regional cooperation, investing in cutting-edge research and development, and developing human capacity–are critical for positioning the region as a leader in green energies.
Introduction
In recent years, resource-rich countries in the Middle East and North Africa (MENA) have played a pivotal role in global energy markets, mainly due to their abundance of oil and natural gas reserves. This has driven the economic growth of resource-rich MENA countries and established them, particularly the Gulf states, as key producers in the global energy supply chain, shaping international energy dependencies and market dynamics. With increasing pressure to put an end to the catastrophic effects of climate change, countries across the globe have been drafting strategies and plans to transition away from fossil fuel production and consumption towards green alternatives. The momentum of the energy transition has raised legitimate questions in the MENA region—especially for the countries which are the main producers of fossil fuels, whose economies depend on this energy. These concerns center around how post-oil economies will affect the future of MENA’s societies and whether governments in the region will still have a role to play in a future less dependent on fossil fuels.
This briefing examines the potential of resource-rich countries in the MENA to capitalize on their natural resources and strategic placement to lead in renewable and green energies. It explores the possible benefits for MENA countries, highlights the importance of regional cooperation, and provides recommendations for achieving sustainable energy leadership in the coming decades.
MENA at the crossroads of the energy transition
The MENA region’s impact on global energy markets is underscored by its substantial contribution to global oil and gas production. As shown in Table 1, five MENA countries—Iran, Iraq, Kuwait, Saudi Arabia and the United Arab Emirates (UAE) —rank among the top ten oil producers worldwide, collectively supplying approximately 26 percent of the world’s oil.
Table 1: Top ten oil-producing countries in 2023
| Country | Oil production (in million barrels per day) | Share of world total |
| United States | 21.91 | 22% |
| Saudi Arabia | 11.13 | 11% |
| Russia | 10.75 | 11% |
| Canada | 5.76 | 6% |
| China | 5.26 | 5% |
| Iraq | 4.42 | 4% |
| Brazil | 4.28 | 4% |
| UAE | 4.16 | 4% |
| Iran | 3.99 | 4% |
| Kuwait | 2.91 | 3% |
| Total Top 10 | 74.59 | 73% |
| World Total | 101.81 |
Source: U.S. Energy Information Administration, https://www.eia.gov/tools/faqs/faq.php?id=709&t=6.
Similarly, as shown in Table 2, four MENA countries—Algeria, Iran, Qatar and Saudi Arabia—rank among the top ten natural gas producers, collectively producing around 16 percent of the global natural gas supply.
Table 2: Top ten natural-gas producing countries in 2023
| Country | Natural gas production (in billion cubic meters) |
| United States | 1,035.3 |
| Russia | 586.4 |
| Iran | 251.7 |
| China | 234.3 |
| Canada | 190.3 |
| Qatar | 181 |
| Australia | 151.7 |
| Norway | 116.6 |
| Saudi Arabia | 114.1 |
| Algeria | 101.5 |
| Malaysia | 81.1 |
| World Total | 4,059.2 |
Source: Energy Institute, https://www.energyinst.org/statistical-review.
The global energy transition from hydrocarbons to renewable energy sources aims to combat climate change and reduce emissions, and it is redefining traditional economic and energy paradigms. Amid this shift, the MENA region stands at a crossroads. Resource-rich MENA nations face a choice: they can either lose the economic power they have held for many years, or seize the golden opportunity to emerge as global leaders in the era of clean energy. Nevertheless, this transition also brings about institutional, organizational, and financial challenges that governments in the region need to address. MENA countries must explore pathways to diversify their energy sectors in order to maintain economic growth and remain competitive in an evolving global energy market. However, governments of resource-rich countries do not have to view the energy transition as a complete shift away from hydrocarbons. Many are adopting policies where both hydrocarbons and renewables contribute to reducing emissions and enhancing energy security.
A win-win scenario for the MENA region
According to the governments of the region, MENA countries can uniquely benefit from a win-win scenario in the energy transition. By leveraging its dual strengths in both hydrocarbons and renewables potentials, the MENA region can drive economic resilience and growth. Its competitive advantage derives from three key factors:
- Dual resource advantage: The MENA region is endowed with a dual foundation in hydrocarbons and renewable energy potential, particularly solar and wind, thus giving it a natural advantage in adapting to the global energy transition. According to the World Bank, 22–26 percent of solar energy is concentrated in the MENA region, allowing it to produce at least half of global electricity needs. Moreover, each unit invested in solar energy is expected to reduce emissions by twice as much as a similar investment in Europe or North America. The region also has abundant unused land that is well suited for large-scale solar farms as well as having untapped potential for wind energy. Large-scale wind projects can be carried out in key locations, such as Morocco’s Atlantic coast, the Gulf of Suez in Egypt, as well as north-western deserts in Saudi Arabia and southern Oman. There are generally fewer challenges in implementing these projects than in Europe or North America, where obtaining permits can be more time-consuming and projects tend to face stronger resistance from local communities. Capitalizing on wind and solar energy could enable the MENA region to also become a hub for green hydrogen production, something that is a high energy transition priority for many governments.
- Balanced economic transition: For resource-rich producing countries, the global energy transition does not imply an immediate shift from hydrocarbons to renewables. Rather, it involves a balanced approach, allowing MENA countries to maintain economic stability through hydrocarbon exports while developing their renewable energy sectors.
- Competitive production in energy-intensive sectors and strategic export advantage: The MENA region could take advantage of its access to low-cost and renewable-based energy to support energy-intensive industries, such as metals and chemicals, thus producing goods with low emissions. It could then export these goods to nearby regions, such as Europe, to transform them into final products. As such, the MENA region would be an attractive production hub for global markets as well as a reliable supplier in the green energy economy.
Regional cooperation: The backbone of MENA’s energy transition
Regional cooperation could be a driving force for the energy transition in the MENA region. Some have the land, while others have the financial capacities, workforce, infrastructure, or political leverage. Gulf Cooperation Council (GCC) countries, particularly Saudi Arabia and the UAE, have been using the hydrocarbons sector and their financial capacities to advance their clean energy transition plans. Other countries, such as Morocco, have been able to attract investment for their projects through gaining knowledge and expertise to negotiate with financial institutions with complex standards. Others, such as Egypt, are attracting investment by catering to the needs of the global north, especially the European Union.
Several energy collaborations and infrastructure projects already exist in the MENA region, showcasing the potential for broader cooperation. These are projects related to hydrogen, renewable energy, electricity and grid interconnectors.
Hydrogen projects
- Saudi Arabia’s green hydrogen initiative: Saudi Arabia is leading the development of the largest utility-scale green hydrogen project globally, set to begin operations in 2026 in Neom. The facility is projected to generate 600 tons of clean hydrogen per day and 1.2 million tons of green ammonia annually. The majority of this is intended for export, with transportation routes to include shipment via the Red Sea, pipelines through Egypt, and overland pathways to neighboring countries. This project is expected to reduce carbon emissions by 5 million metric tons annually, showcasing Saudi Arabia’s commitment to sustainable energy.
- Egypt’s hydrogen agreements: At COP27, Egypt advanced its ambition to become a regional hydrogen hub by signing eight memorandums of understanding. These agreements include plans for an $8 billion hydrogen plant in the Suez Canal Economic Zone.
- Morocco’s hydrogen roadmap: Morocco aims to establish a thriving hydrogen market, targeting a local demand of 4 TWh and exports of 10 TWh by 2030. This plan requires the development of 6 GW of new renewable energy capacity to support its ambitious goals.
- Hydrogen pipelines and infrastructure: Proposals are being explored to establish a network of hydrogen pipelines connecting Israel, Jordan, Oman and the UAE. These pipelines could facilitate collaboration among these countries, leveraging existing natural gas infrastructure to transport hydrogen to regional and global markets.
Renewable energy projects
- Saudi Arabia’s renewable energy in Neom: Saudi Arabia aims to produce 4 GW of renewable energy, with 3 GW allocated specifically to power its green hydrogen plant in Neom, demonstrating its commitment to integrating renewable energy into its projects.
- Project prosperity: At COP27, Israel, Jordan and the UAE agreed on a water-energy swap initiative. This project includes the construction of a 600 MW solar PV plant in Jordan, which will supply electricity to Israel in return for desalinated water. Developed by Masdar, a UAE state-owned company, this collaboration underscores the advantages of regional cooperation in addressing energy and water challenges.
- Egypt’s renewable energy advancements: Egypt is rapidly increasing its renewable energy capacity through large-scale solar PV projects. A notable example is the Benban Solar Park in Aswan, which has a capacity of 1,650 MW and reflects Egypt’s dedication to clean energy development.
- Renewable energy potential in conflict-affected areas: The Sinai Peninsula in Egypt and the West Bank possess considerable potential for renewable energy projects. However, significant political and security barriers must be resolved to unlock these opportunities.
Electricity grids
- GCC grid: The GCC operates a reliable electricity grid for emergency and peak-load scenarios.
- Mashreq grid: The Mashreq grid connects countries such as Egypt, Iraq, Jordan, Lebanon, Libya, the Palestinian territories, Syria, and Turkey, though it has been less effective than other regional grids.
- Maghreb grid: North African countries such as Algeria, Libya, Mauritania, Morocco, and Tunisia use this grid for electricity trade.
- Egypt-Saudi Arabia interconnector: The Egypt-Saudi interconnector project aims to enhance electricity trade between the two countries, with plans for significant capacity expansions.
- Regional grid interconnection: Projects such as Israel-Jordan connections (as part of Project Prosperity) and Egypt-Cyprus-Greece interconnectors are under way, aiming to link MENA grids with Europe for better energy integration.
By cooperating, MENA countries can create a connected energy infrastructure that enhances regional competitiveness and facilitates access to global markets. Regional cooperation also enables the strategic placement of renewable energy stations across diverse areas, allowing for more efficient resource use. A well-connected or unified market would attract foreign investment more effectively, transforming natural resources into economic opportunities and solidifying the region’s position in the global green economy.
MENA countries are richly endowed with renewable resources and are deploying energy projects at varying paces under diverse policy frameworks. While many of these projects depend on imported technologies, such as solar PV panels, countries like Morocco and Tunisia have begun integrating elements of renewable technology value chains locally. Expanding this integration at a regional level presents a significant opportunity for collaboration across the MENA region. By adopting a coordinated approach, countries can leverage regional expertise in industries such as metals, mechanics, and electronics to develop complementary links in renewable technology value chains.
A strategy based on regional integration would not only create a larger market for renewable technologies, but also encourage manufacturers to scale operations and foster the creation of new businesses. Healthy competition among manufacturers in different countries could further drive productivity, innovation, and resilience against global competition. Additionally, a regionally integrated approach could optimize supply chains by reducing transportation distances, lowering carbon emissions, and improving overall efficiency. Such efforts would not only strengthen the renewable energy sector but also position the MENA region as a leader in the global energy transition.
The private sector: A catalyst in MENA’s energy future
In the MENA region, the energy sector—that is mainly electricity companies and those in oil and gas production—has generally been dominated by government-led investments. However, the need for private sector involvement in the energy transition is becoming increasingly apparent. Governments alone cannot shoulder the financial burden of meeting the region’s growing energy demands, especially as populations expand and economies industrialize. Most governments plan to replace the local energy needs from fossil-based fuels to clean energy, and this requires not only public investments in renewable projects but also a more active role for private companies that will need financing from different public and private sources.
Despite its potential, the private sector in the MENA region faces several challenges in contributing to the renewable energy transition. One of the primary obstacles is the capital-intensive nature of renewable energy projects, which requires developers to secure financing from banks or other financial institutions at the best prices and terms. Additionally, suppliers and contractors face significant pressure to deliver projects at the lowest possible cost while meeting stringent specifications, further complicating the process.
The overwhelming demand for renewable energy infrastructure has also created intense competition for supply chains, natural resources, and construction contractors, as the volume of demand exceeds the available supply on all levels. Companies like the Saudi and the Emirati Masdar have demonstrated global competitiveness by securing projects in Eastern Europe, Central Asia and South Africa. However, even these industry leaders face significant challenges—including navigating strained supply chains and securing favorable financing—as nations worldwide accelerate their renewable energy agendas. The broader market continues to struggle with establishing institutional frameworks and implementing effective risk-mitigation mechanisms to support project financing and attract global capital. Addressing these issues requires governments to prioritize investments in regional infrastructure and create environments that encourage private-sector participation. No single country’s resources are sufficient to meet the ambitious targets alone.
A key strategy to incentivize private-sector participation in the energy transition is for governments to encourage partnerships between small businesses and established companies. These collaborations enable smaller firms to gain expertise, thus equipping them to operate independently in the renewable sector. Governments can also play a critical role by committing to long-term purchase agreements for the produced energy, providing investment security and reducing risks for investors. For example, companies like ACWA Power and Masdar have benefited from such frameworks, enabling them to secure competitive financing and deliver large-scale renewable energy projects within and beyond the MENA region. This highlights the importance of creating regulatory environments that encourage private sector participation.
Establishing frameworks that attract global capital is equally important, as it ensures the scalability of projects beyond the capacity of domestic resources. Government resources can serve as seed funding to attract larger private investments, both domestically and internationally. Moreover, creating a regulatory and legal environment that protects and encourages investment—whether from local or foreign entities—is essential. MENA governments should also prioritize cross-border collaborations and public-private partnerships to establish an institutional framework that fosters private-sector growth and regional integration. Cross-border initiatives involving companies like ACWA Power and Masdar show how regional cooperation can amplify the impact of renewable-energy investments. These companies have initiated projects that not only strengthen local energy infrastructure, but also connect MENA markets to global energy systems. Combined with focused investments in regional infrastructure, these strategies can significantly enhance the region’s capacity to meet its ambitious renewable energy targets.
Recommendations for strengthening collaboration on MENA’s energy transition framework
To be established as a pioneer and leader in renewable energy—and to be able to produce enough green energy to suffice local demands and export the excess—governments in the MENA region should undertake several strategic actions to move toward complementarity, integration, collaboration, and exchange:
- Develop energy infrastructure and regional connectivity: MENA governments should prioritize policies that enhance green infrastructure and establish connections with neighboring countries. Establishing a reliable and integrated electricity network would support the efficient distribution of renewable energy across the region, providing ease of access and strengthening energy security.
- Maintain low-cost and high-reliability hydrocarbon electricity: Amid the transition to renewable energy, MENA governments should capitalize on their existing hydrocarbon resources to reliably produce electricity at a low cost. In this way, they can retain economic stability and allocate hydrocarbon revenues to fund projects based on renewable energy.
- Encourage energy-intensive industries: MENA governments should attract industries that rely heavily on energy to transform their industries by focusing on clean electricity and green hydrogen. Providing low-emission products could transform the region into a competitive renewable production hub.
- Invest in research and development: Investment in research and development is crucial to exploring innovative uses for clean energy. Governments can advance the application of renewable energy in sectors like green agriculture, for example, by investing in cutting-edge research and development.
- Enhance human capacity: MENA governments should develop the local expertise in both traditional and renewable energy sectors by equipping the workforce with the necessary skills. For example, governments could invest in training programs that upgrade the skills of those working in the oil and gas sector to meet the demands of a renewable-focused economy.
- Create a favorable investment environment: MENA countries should establish a favorable organizational and legal framework, which will help attract local and foreign investment. Government policies that protect investments and reduce risks will stimulate private-sector participation in renewable energy projects. Government funding should serve solely as seed capital in order to stimulate larger investments.
- Develop a regional roadmap for the energy transition: MENA countries should collaborate on a comprehensive regional roadmap, similar in structure to the European Green Deal, to guide them through the energy transition. The MENA Green Dealshould outline infrastructure needs, such as integrated electricity connections, and establish organizational and legal frameworks to support renewable energy development. Moreover, it should define the role of the private sector and provide incentives for investment in renewables, critical minerals, and research and development.
References
Coleman, L. (2024, April 25). World Economic Forum. “This is how the MENA region can accelerate its renewable energy production”. Retrieved from https://www.weforum.org/stories/2024/04/renewable-energy-capacity-mena/.
Energy Institute. (2024). Statistical Review of World Energy. Retrieved from https://www.energyinst.org/statistical-review.
Ezrahi, A. (2024). An Energy and Sustainability Road Map for the Middle East. Atlantic Council. Retrieved from https://www.atlanticcouncil.org/in-depth-research-reports/report/an-energy-and-sustainability-road-map-for-the-middle-east/#specific-initiatives.
International Energy Agency. (2024). Natural gas information: Database documentation (2024 edition). Retrieved from http://wds.iea.org/wds/pdf/gas_documentation.pdf.
Natural Resource Governance Institute. (2024). ندوة عبر الانترنات : الثروة المعدنية وتعزيز التعاون الإقليمي في الشرق الأوسط وشمال أفريقيا. YouTube video. Retrieved from https://www.youtube.com/watch?v=gGzXRGdI2rQ.
U.S. Energy Information Administration. (2024, April 11). “Frequently Asked Questions (FAQs) – What countries are the top producers and consumers of oil?”. Retrieved from https://www.eia.gov/tools/faqs/faq.php?id=709&t=6.
World Economic Forum. (2023). Closing the Climate Action Gap: Accelerating Decarbonization and the Energy Transition in MENA. Retrieved from https://www3.weforum.org/docs/WEF_Closing_the_Climate_Action_Gap_2023.pdf.
Acknowledgements
This briefing is part of the Natural Resource Governance Institute’s (NRGI) contribution to the just energy transition debate in the Middle East and North Africa. The content has been developed through discussions between the author, Laury Haytayan (MENA director at NRGI), and Dr. Shihab Elborai, partner at Strategy& Middle East and co-author of Arabian Gambit: The path to leadership in a shifting global energy landscape.
Insights and Lessons from Global JETP Experiences

As Senegal embarks on its journey toward a sustainable energy future through the historic Just Energy Transition Partnership (JETP), civil society has a critical role to play in shaping this transformation. With €2.5 billion committed by global partners, this initiative is set to significantly expand the role of renewable energy in Senegal, reducing dependence on fossil fuels and ensuring a just transition for all.
But how can civil society organizations (CSOs) effectively engage in this process and influence the decision-making?
What was covered
- CSO experiences from Vietnam, South Africa, and Indonesia: Lessons learned, challenges faced, and opportunities seized in their JETP journeys.
- Government perspectives from these countries on engaging with civil society in the design and implementation of energy transition plans.
- Actionable insights for Senegalese CSOs on how to ensure transparency, citizen rights, and accountability in the JETP process, and how to align it with Senegal's renewable energy goals.
Key speakers
- Birgit Strube: Head of the Climate Partnership Division, BMZ (German Federal Ministry for Economic Cooperation and Development)
- Awa Ndione Sène: Coordination and Monitoring Unit for the JETP (UCS-JETP) - Ministry of Energy, Petroleum, and Mines
- Blessing Manale: Executive head, consensus building and outreach at the Presidential Climate Commission (PCC) - South Africa
- Abraham Octama Halim: Power System Analyst at Institute for Essential Services Reform (IESR) - Indonesia
- Fatima Diallo: Executive director at CRADESC and Lead of the Civil Society Actors Platform for a Just Energy Transition in Senegal (PACTEJ) - Senegal
Moderator: Nafi Chinery - NRGI Africa Director
Organizing and Facilitating: Aida Diop - Senegal Senior program officer; Ousmane Touré - Communications officer
Power to the People: Perspectives on Nigeria’s Energy Transition Plan

Nigeria’s economy is the largest in Sub-Saharan Africa, with vast natural resources including oil and the continent’s largest gas reserves. However, according to the International Energy Agency, over 140 million Nigerians—70 percent of the country’s population—lack access to energy. In response, the government of Nigeria aims to achieve universal energy access by 2030 and is implementing several policies and initiatives to increase access to clean and affordable energy for its citizens. But how can the government achieve this ambitious goal?
“Empowering communities with reliable and affordable energy is not just a necessity; it is a catalyst for socio-economic progress. It fuels education, healthcare, and economic activities, paving the way for sustainable development” says Enebi Opaluwa, a senior research and policy analyst at BudgIT Nigeria, and a participant in the 2023 edition of the advanced course “Natural Resource Governance and Energy Transition: Policies and Practice”, co-organized by NRGI and the NADEL Center for Development and Cooperation at ETH Zurich. (The 2024 edition starts next week.)
After the course took place, we spoke with Nigerian participants, most of whom chose to focus on maximizing community benefits and managing diversification during the course. By enrolling in this path, participants learned about policies to enhance citizen engagement and mitigate socioeconomic impacts and conflicts related to extraction. They also studied tools for managing revenue distribution at the national and subnational levels, and the implementation of local content policies and national and local development plans.
A financing gap and changing regulations
“In Nigeria, many of the current policies and efforts to increase energy access are directed toward ensuring increased access to electricity for clean cooking, clean sources of energy, and energy transport, but there are gaps and barriers that prevent these policies from achieving their goal, including affordability, cultural factors and financing,” says Opaluwa.
“Financing is a key issue,” agreed Agwu Ojowu, a senior consultant for Africa Practice. He points out that the Nigerian government faces financial constraints in investing in the necessary energy and infrastructure system for delivering energy from new sources to citizens. The challenge is exacerbated in highly regulated markets, where existing providers discourage private investment needed for cleaner energy sources. Excessive regulation and market capture dynamics make it difficult for new players to enter these markets, posing obstacles to the introduction of more sustainable energy solutions
In response to this challenge, the Nigerian government passed a constitutional reform bill that allows individual states within the country to supply electricity, breaking the monopoly of the federal government over power provision. State governments can now independently explore the electricity generation business and transmit and distribute electricity in areas covered by the national grid and in remote areas. “This dually regulated system is less convoluted and allows the government to,” says Ojowu. This new process and innovation must be managed appropriately, with strong frameworks to build the capacity of states to manage this new development, the participants agreed.
In alignment with the participant’s perspective on the recent bill empowering individual states to supply electricity, the potential for state governments to distribute electricity across the national grid and in remote areas is a notable opportunity. However, Chichi Nwosu, a principal consultant at CRowland, a Nigerian development consultancy, underscores a significant challenge. She points out that the lack of employment opportunities stands as a major barrier, hindering local communities from reaping the benefits of this opportunity. This obstacle is rooted in socioeconomic implications and the unaffordability of social security for these communities. Addressing this employment gap becomes crucial for ensuring that the positive outcomes of the new bill are more inclusive and impactful for local populations.
“Emphasizing community engagement from the outset is paramount for fostering investments and ensuring that policies resonate with and benefit the local population.” - Agwu Ojowu
“Having well-crafted policies and legislation is crucial, and effective implementation is essential. However, without active involvement from local communities during the development stage, the successful implementation and dissemination of these policies become challenging,” explains Ojowu. “Emphasizing community engagement from the outset is paramount for fostering investments and ensuring that policies resonate with and benefit the local population.” Many communities exhibit “cash upfront rent-seeking behavior” whereby they agree to receiving cash handouts at the start of projects taking place locally. He argues that this has prevented local communities from benefiting from extractive projects and playing an active role in the sustainable development of their local economy because it precludes more significant investments in infrastructure, health services that would likely be more beneficial to communities in the long run.
Communities need education on the energy transition
“There is a need to raise awareness and sensitize local communities on the energy transition,” says Kolawole Kolade, a program officer on climate change adaptation and energy accountability at the Paradigm Leadership Support Initiative. Kolade explains that it is essential for government officials and civil society organizations to involve local communities in the decision-making and policy-making processes, so that citizens can actively understand the impact the transition has on the socio-economic development of their communities.
Community and stakeholder awareness is particularly important in the context of Nigeria’s new Energy Transition Plan, explains Nwosu. The plan was developed with the ambitious goal to achieve net-zero emissions in terms of Nigeria’s energy consumption. “This is a bold plan,” says Ojowu. “There is a need to build a climate change awareness culture in Nigeria.” He believes that authorities should include climate change awareness in curricula across all levels of education. He says that citizens across the entire country should be aware of what the climate change adaptation and mitigation measures the government can take—and that they, the citizens, must ensure that these goals are met. Enebi adds that the government should propose and implement education courses and other initiatives (including public hearings and media campaigns) to educate the population on the energy transition and its impacts, both at the national and local level.
Giving communities a role and a voice
“Currently, there is a gap between central and national governments, particularly when it comes to the energy transition agenda,” adds Enebi. He says that the energy transition plan focuses on attracting investments, but it lacks specificity about the federal government’s responsibilities going forward, as well as ways in which local communities can participate in to ensure the plan moves in the right direction.
“Even at the subnational level, relevant actors do not thoroughly understand what their role is in the context of the energy transition and climate change.” - Kolawole Kolade
Enebi suggests that civil society organizations advocate for clearer milestones and ways to measure the plan’s progress. One way government authorities could achieve this could be by incorporating citizen participation in budgetary processes, whereby the government provides citizens with easily digested information around budgeting during the approval and audit stages, so that they can participate and play an active role at the approval stage during public hearings. “This process should be applied to the energy transition plan,” says Enebi.
“Even at the subnational level, relevant actors do not thoroughly understand what their role is in the context of the energy transition and climate change,” says Kolawole. “There is a need at the federal level to create a framework for subnational governments to look into their responsibilities and have a tool to track their progress.” Civil society organizations should drive engagement and bridge the gap between the government and local communities on knowledge gaps around the energy transition plan, he adds.
Environmental concerns
“Environmental injustice should also be an important pillar of the energy transition plan,” says Enebi. “The energy transition will happen, but at the cost of the environment.” The plan should focus on ensuring that this conversation is at the forefront of discussions among Nigeria’s key decision-makers, politicians and local communities. This is particularly important as international oil companies increasingly divest assets to national oil companies leaving extant environmental pollution unremediated, Enebi adds.
Ojowu suggests that while engaging with local communities, the government should prioritize environmental regulation that is inclusive and consultative, fostering economic activities and alternative livelihoods beyond the oil sector. This is key in ensuring that local communities rely to a greater extent on other sectors, such as fishing and other sources of livelihood, so that there is a sustainable future that does not depend on oil or encourage oil pollution.
A unique learning opportunity
Regarding the advanced course itself as a platform to reflect on Nigeria’s challenges and opportunities in the context of the energy transition, participants particularly valued engagement with other participants from all over the world. “The peer-to-peer learning has allowed me to understand the similar challenges that other countries are currently facing,” said Enebi. “This has been very helpful in identifying potential opportunities and solutions.”
Ojuwu particularly enjoyed learning more about the tax and budget aspects of natural resource governance. The technical knowledge provided during the path on local communities allowed Kolade to further explore Nigeria’s gaps when it comes to community engagement tools, and this is something he is excited to continue working on. And Nwosu highlighted the importance of meeting participants who are active in same space, and how this enables them to share knowledge and collectively drive change with the aim of pushing for a just and inclusive energy transition.
The advanced course empowers participants to improve natural resource governance, especially around the energy transition.