
As the West Turns Inward, Can Africa Leverage Its Mineral Power?

In the few months since Donald Trump returned to power, a flurry of decisions has made ‘restoring America’s mineral dominance’ a key priority for the administration. These range from strongarming Ukraine into providing access to mineral (and energy) assets in exchange for continued support in its war with Russia, to designs on Greenland. Trump has also issued executive orders to increase domestic mineral production and processing, weaken due diligence in the financing of mining projects and pause anti-bribery protections to gain “strategic business advantages” in accessing minerals overseas.
Other consumer countries’ approaches have also become clearer in recent months. Changing political winds in the European Union (EU), following the 2024 European Parliament elections, have reaffirmed a focus on ramping up domestic supply amid a deregulation drive. The first batch of strategic projects for development under the Critical Raw Materials Act focuses exclusively on projects within Europe—excluding applications from other regions.
For African mineral-producing countries, this moment presents new risks—but also an opportunity to strengthen their position. International politics around minerals have long been at the intersection of economic and national interests, but the new U.S. administration is now pushing it into even more transactional territory. Through its rhetoric and actions, the U.S. government is signaling that multilateral engagement and good governance standards are no longer its priorities.
African decision-makers are already considering how to navigate this new terrain. Facing the advance of M23 rebels in its eastern provinces, the government of the Democratic Republic of the Congo (DRC) has sought to make a “deal” to leverage its minerals in exchange for security assistance from the U.S. To use the global context to their advantage, decision-makers will need a long-term vision for their economies—grounded in evidence, political acumen and strong alliances.
Analyze your leverage—and carefully weigh what you gain and give up in any deal
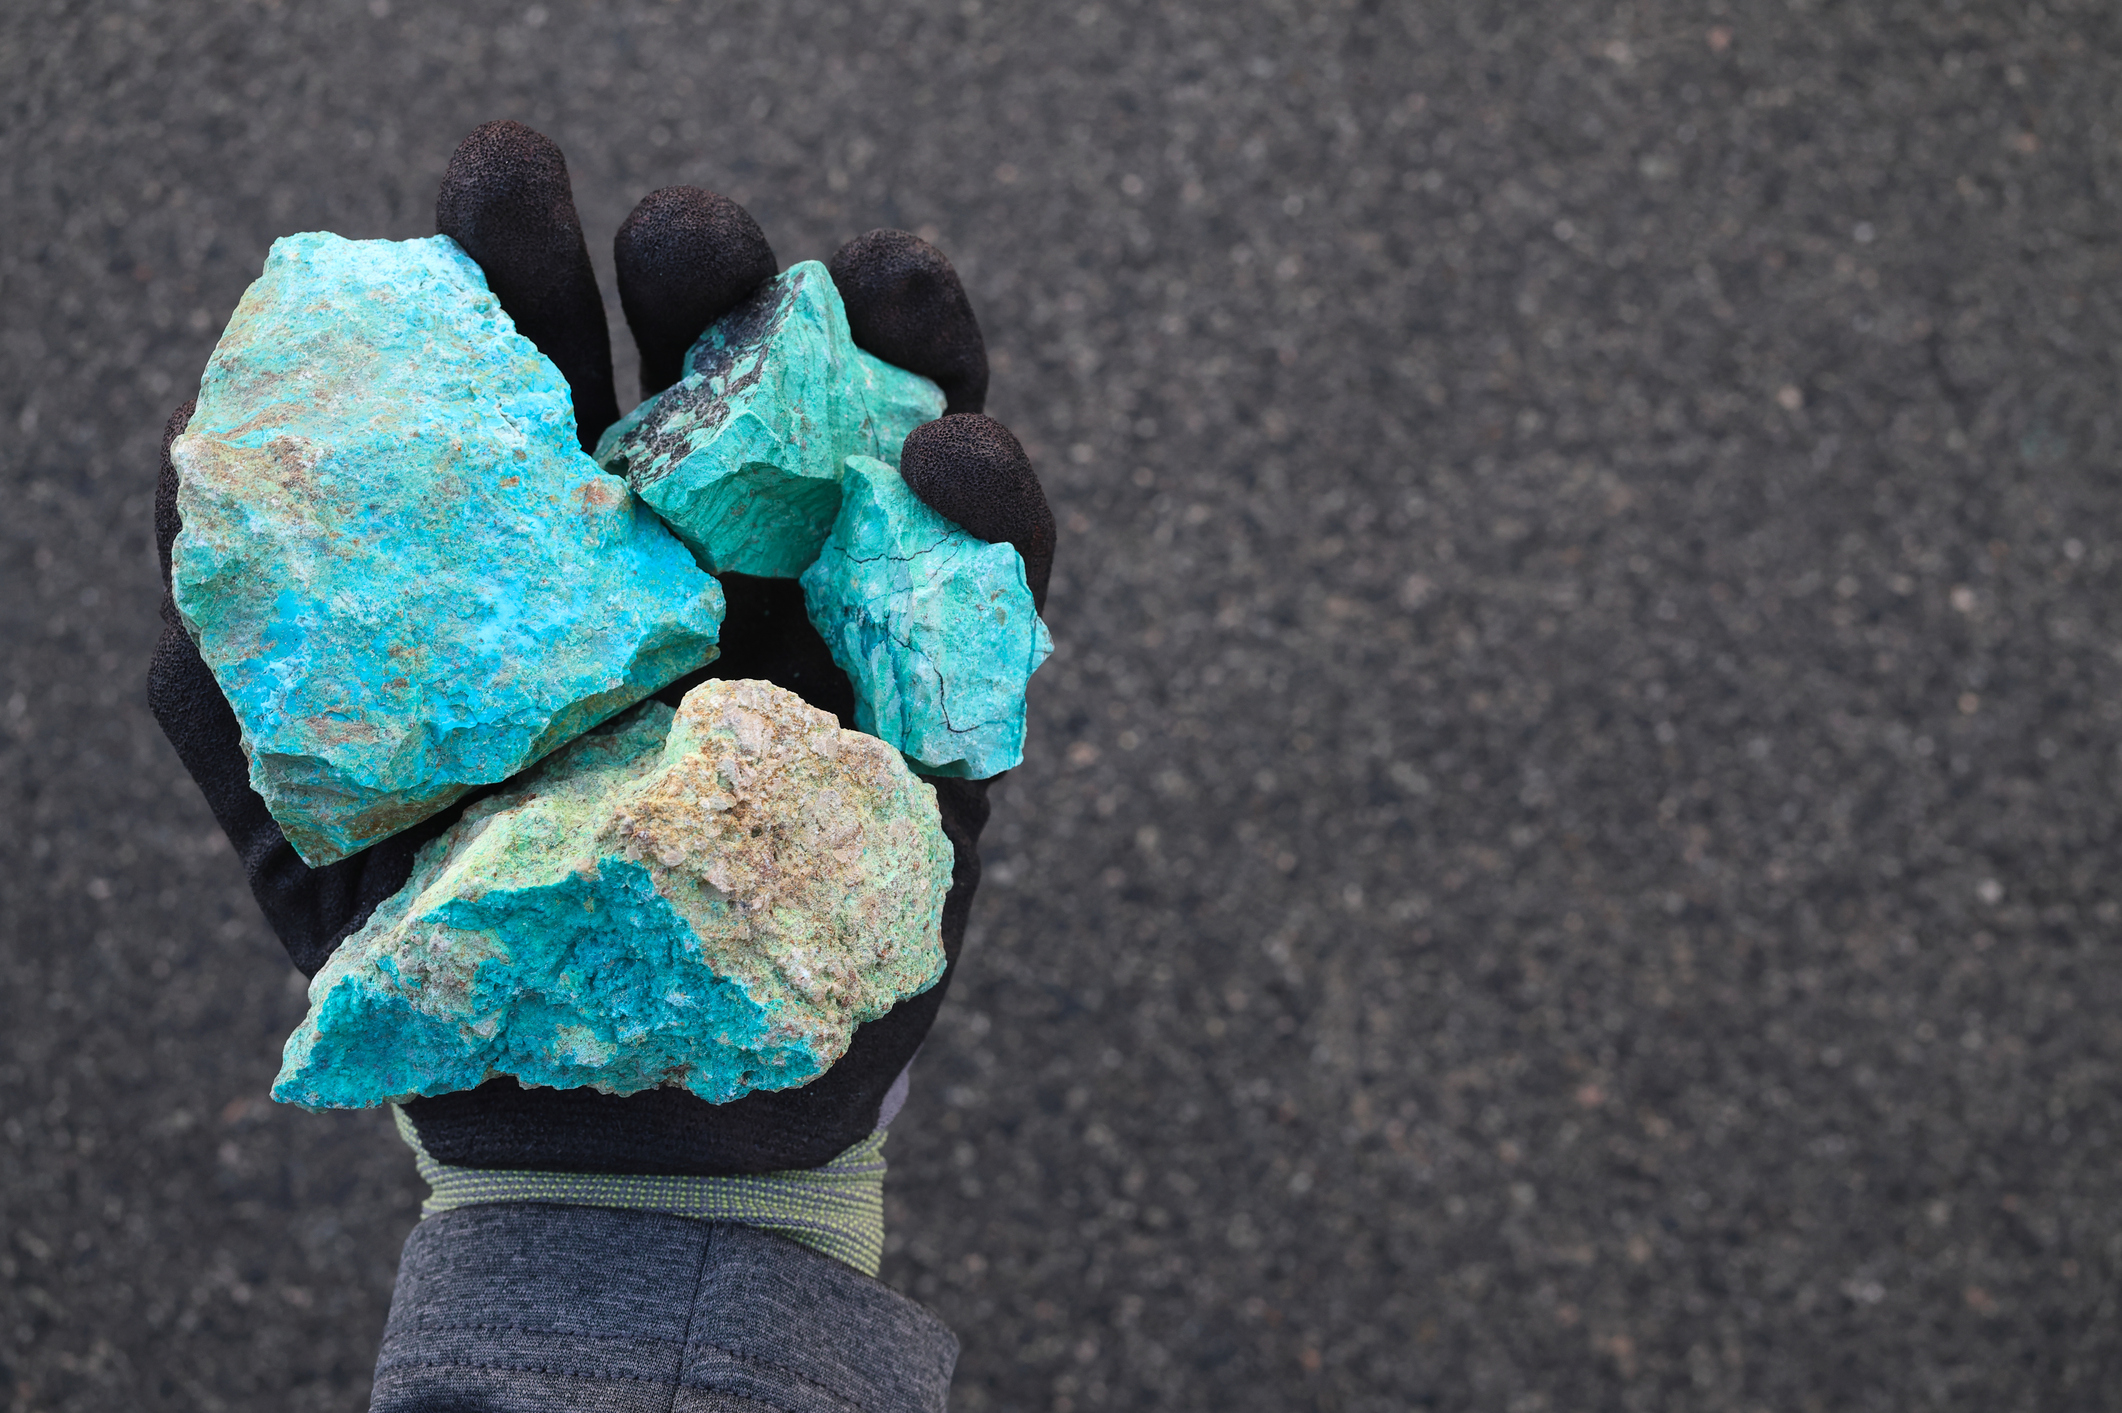
African bargaining power remains real, particularly as the U.S. looks to counter China’s dominance. Africa holds at least a fifth of the world’s reserves in minerals critical for the energy transition—the U.S. can’t afford to ignore threats by the likes of South Africa to withhold minerals.
As the American diplomatic apparatus kicks into gear around minerals, African governments could gain access to new financing opportunities—even as traditional aid budgets are slashed or disappear entirely. The U.S. International Development Finance Corporation (DFC)—created under Trump’s first term—may play a growing role in providing public finance to catalyze greater private investment. The DFC has backed overseas minerals projects such as a graphite mine in Mozambique, and now has authority to invest in domestic minerals—despite a mixed track record at home. The U.S. and UK are also looking to Export Credit Agencies to take a greater role in the sector, though these institutions have come under fire for harmful practices.
Such financing mechanisms could form part of a bilateral deal centered on mining. In principle, these deals could unlock access to political, financial and technical resources beyond what private investors offer—such as support for geological mapping, derisking exploration investments or infrastructure development. As the DRC’s proposal shows, some countries may seek to leverage this moment to advance broader national goals—such as improving security.
To take advantage of these opportunities, African governments should root their ambitions in long-term strategies based on national development plans. A thorough understanding of their country’s resource base is critical, along with a proactive awareness of how evolving global supply chains, markets and geopolitics affect their bargaining power. We’ve seen the art of the possible: in recent negotiations of a new agreement with De Beers, Botswana increased its share of diamonds for domestic processing from 25 percent to a possible 50 percent by the time that the agreement expires. The DRC government is leveraging its dominant market position to restrict cobalt exports to maximize benefits for the country.
Despite the global shifts, African governments can draw on years of experience in managing their minerals sector. The deals being explored today—such as those in DRC and Ukraine—have parallels in the resource-for-infrastructure arrangements some African governments negotiated with their Chinese counterparts over the past two decades, such as the DRC-China Sicomines deal. These complex negotiations need careful work to fairly value mineral assets and rigorously assess the projects being offered in return. Minerals-for-security deals demand more caution. Security assistance is even harder to value and monitor and often entails greater opacity given national security concerns. Any deal that is agreed must ensure implementation is measurable, transparent and subject to formal oversight.
Regional collaboration for collective leverage
One of the most effective ways that African governments can achieve their development goals is through increased regional collaboration. This is more important than ever in an increasingly turbulent and fragmented world. Trump’s ‘America First’ stance and aggressive tariffs are straining relations between traditional allies in the Americas, Europe and Asia. Multilateral efforts such as the Minerals Security Partnership will likely play a diminishing role in U.S. calculations. However, other partners may still have an interest in working together without U.S. leadership.
Strengthening intra-regional trade through the African Continental Free Trade Area (AfCFTA) and regional economic communities can help mitigate the effects of global geopolitical shifts. While politically and technically complex, a coordinated approach to minerals would strengthen the continent’s collective leverage, prevent a “race to the bottom” and create opportunities for regional value chains that could attract external support. The Lobito Corridor—partially funded by the U.S. under the Biden administration—risks reinforcing the pit-to-port model, but also shows what’s possible when multiple African governments align efforts and partner with external actors.
The African Union’s endorsement of the African Green Minerals Strategy in February 2025 is a significant step towards collaboration—but much work remains. More industrialized African countries must lead the charge, promoting opportunities in less developed neighbors and—alongside development partners—fund regional bodies to increase planning capacity.
Embracing strategic neutrality
Despite renewed global attention, U.S. investment in minerals in the past few years remains minimal. As of late 2023 (the latest data available), the DFC had invested only USD 270 million on mining projects. By contrast, Chinese overseas mining investment reached another high of $21.4 billion under the Belt and Road Initiative in 2024. Whether increased U.S. bluster translates into increased financing remains uncertain.
Even if U.S. support increases, there is no guarantee it will unlock private investment. Despite renewed interest by Western companies in the DRC, for example, the country has struggled to attract investment in recent years due to concerns related to tax, corruption, and other risks. To make the most of these opportunities, African governments must ensure that their policies create a conducive environment for investment.
Strategic neutrality among potential investors is also critical. Failing to do so risks leaving countries empty-handed—especially given the uncertainty of Western investment. It also risks entangling African governments in great power politics. Some governments have had success in this balancing act: Zambia has taken an “all of the above” approach, securing U.S. investment in the Lobito Corridor, Chinese rehabilitation of the Tazara railway and a partnership with the EU.
Hold the line on good governance
Good governance remains critical to enabling long-term and equitable benefits from the mining sector—yet it faces new challenges. In the U.S., Trump is dismantling anticorruption infrastructure at alarming pace. Once a global leader in enforcing restrictions on foreign bribery, the U.S. has now paused enforcement of the Foreign Corrupt Practices Act via an executive order. Amid the scale and speed of U.S. backsliding, troubling changes are also taking place elsewhere. The EU is considering proposals that would gut groundbreaking sustainability legislation, such as the Corporate Sustainability Reporting Directive and Corporate Sustainability Due Diligence Directive.
These rollbacks may embolden some mining companies to push for laxer conditions in African countries—or use corrupt means to secure them. NRGI’s research shows that companies based in the world’s wealthiest and most powerful jurisdictions are often behind corruption cases in the allocation of transition minerals projects. With these jurisdictions now competing for mineral dominance, by holding the line on good governance, African leaders can protect their people and the planet—and prevent disruptions to mining operations such as community blockades, labor strikes or tax disputes.
Embedding transparency and accountability principles into decision-making—through measures, such as contract transparency or parliamentary approval for major agreements—are essential in this more fraught environment. Ghana’s parliament has created space for essential public debate on weaknesses to be addressed as it reviews the country’s first lithium mining agreement. Countries like Niger, Republic of the Congo, Senegal and Sierra Leone are meeting good practice by disclosing contracts under the Extractive Industries Transparency Initiative (EITI); other African countries could follow their lead.
Amid global turbulence lies an opportunity for African leadership. With a clear strategy, stronger regional collaboration and a strong commitment to governance, African governments can navigate the current storms—and turn them into their advantage.
Authors
Papa Daouda Diene
Senior Economic Analyst, Francophone Africa
Nafi Quarshie
Africa Director
Susannah Fitzgerald
Critical Minerals Governance Senior Officer
Thomas Scurfield
Senior Economic Analyst