
Riskier Bets, Smaller Pockets: How National Oil Companies Are Spending Public Money Amid the Energy Transition

-
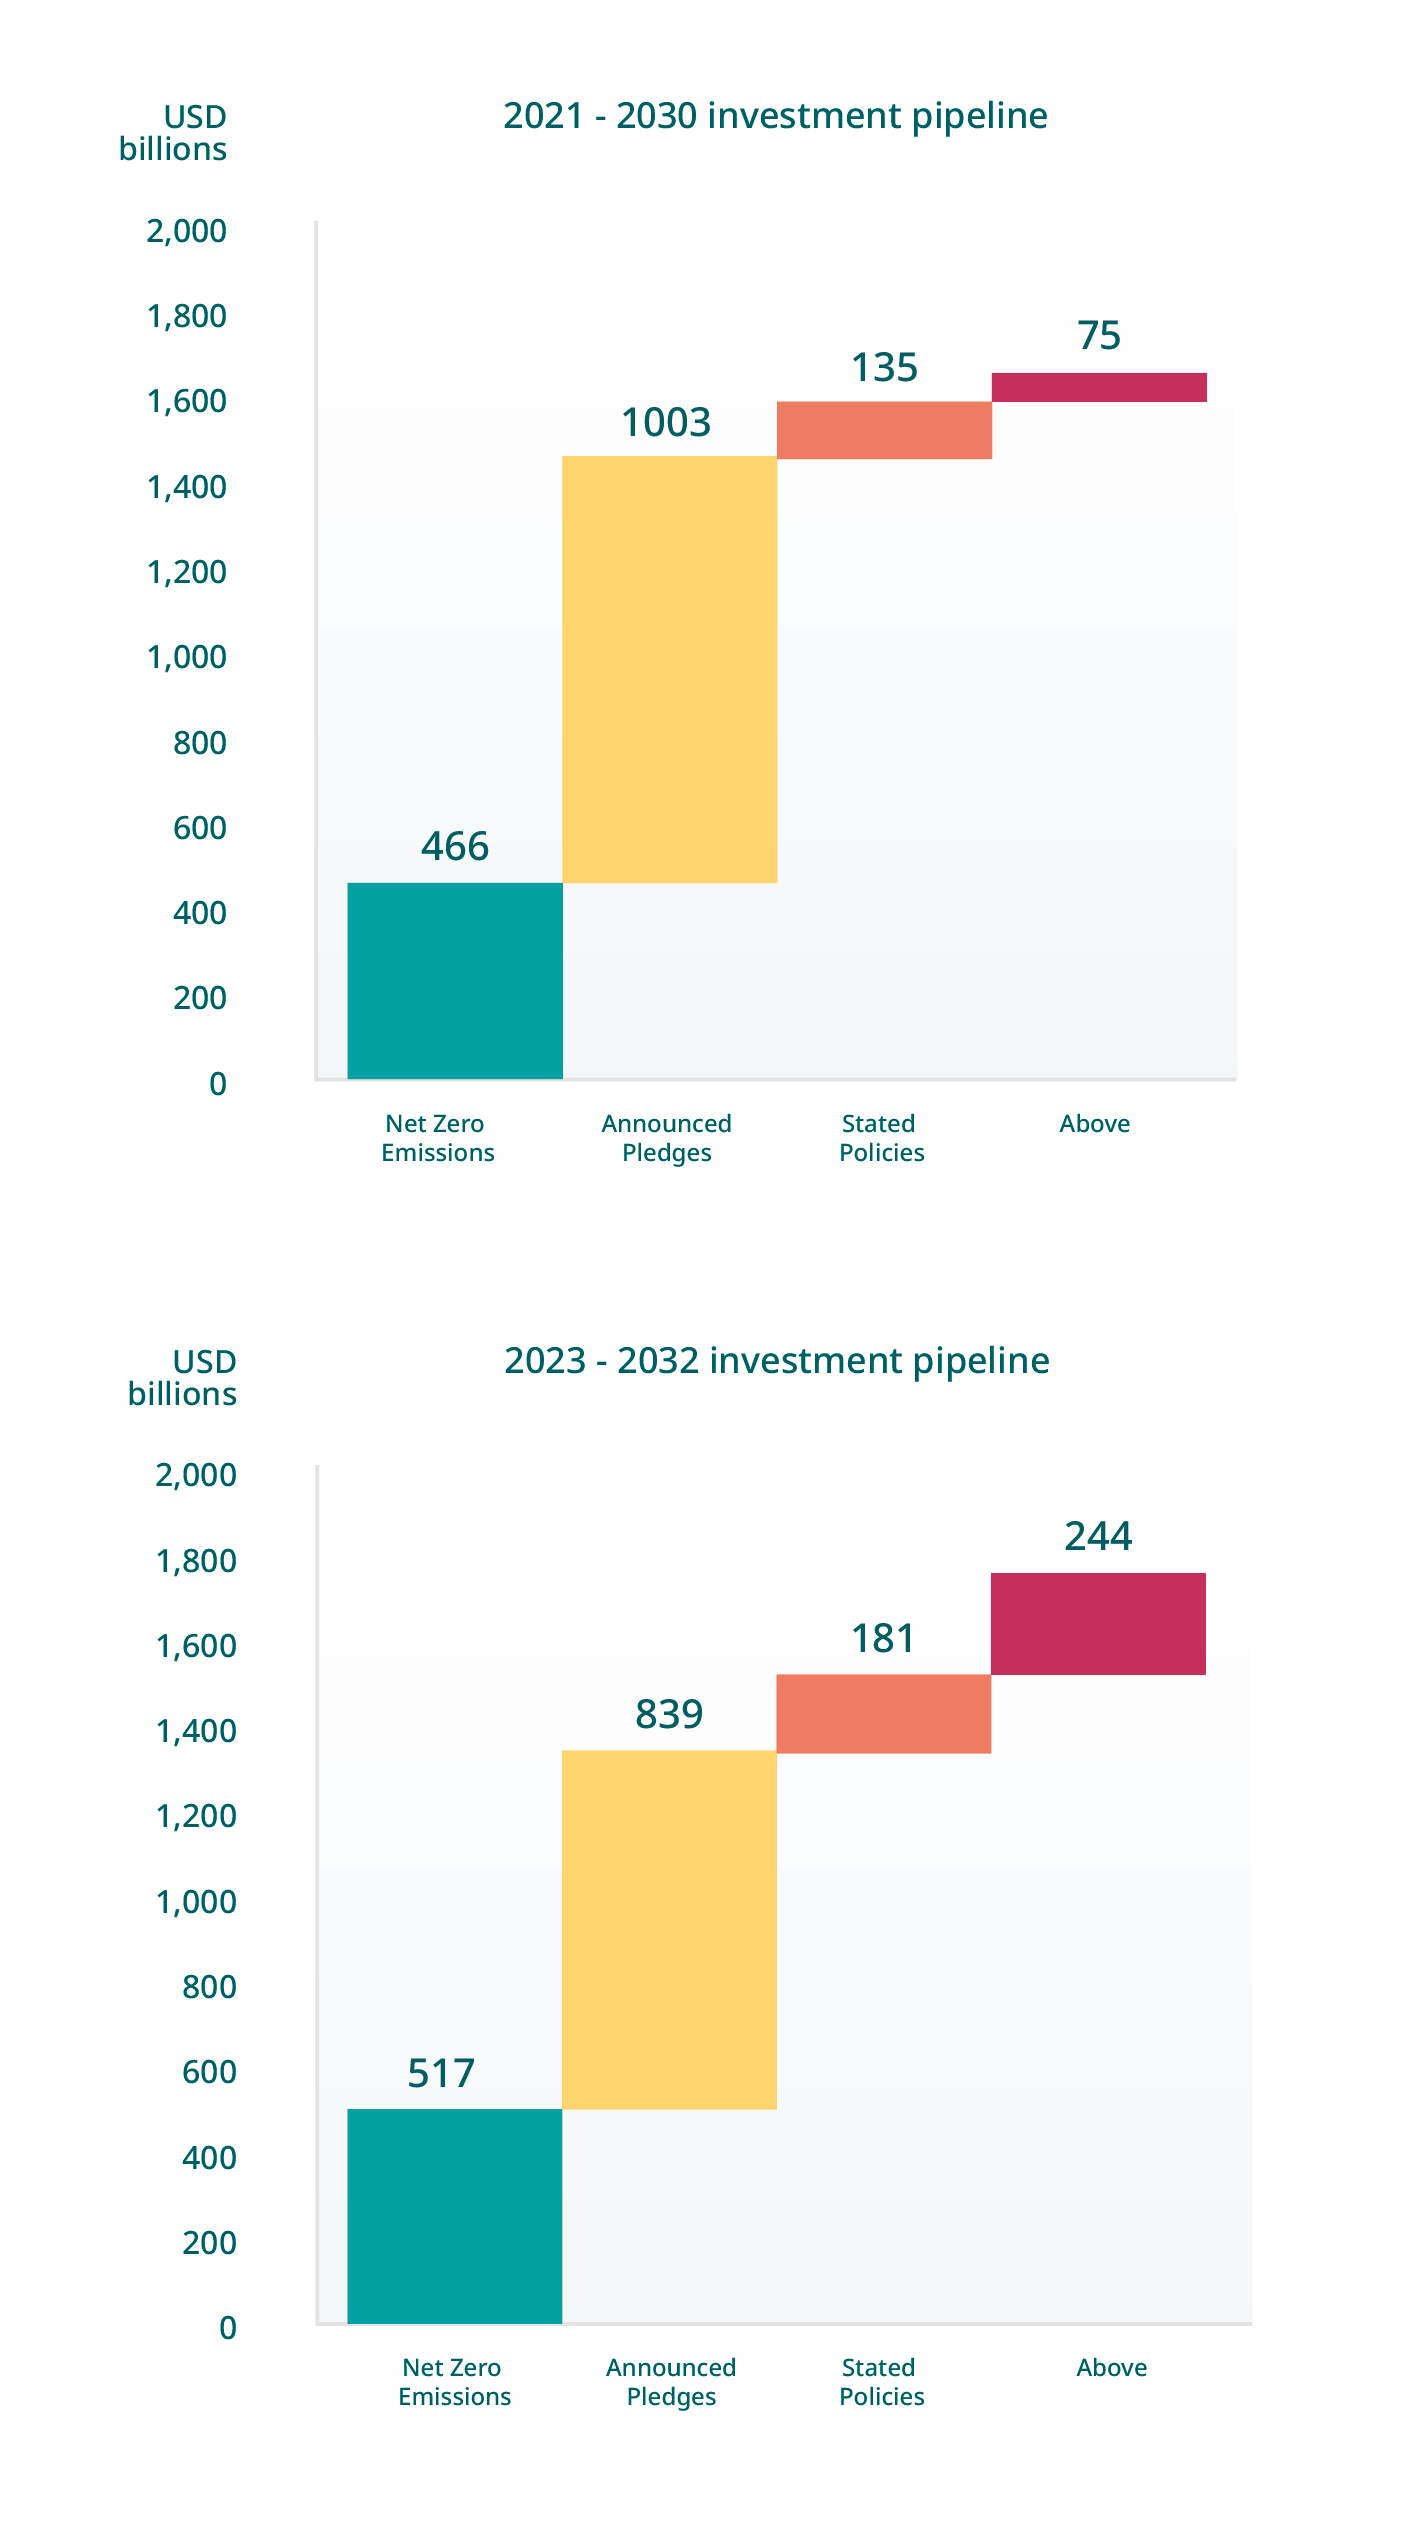
Expecting a slow energy transition away from fossil fuels, national oil companies (NOCs) will likely invest USD 1.8 trillion in upstream oil and gas developments and expansions over the next 10 years.
-
But $425 billion—a quarter of the NOCs’ planned investment—will be unprofitable if oil demand falls to 55 million barrels a day, in line with the International Energy Agency’s Announced Pledges Scenario. This is the highest risk portion of the portfolio and has doubled since the Russian invasion of Ukraine.
-
NOCs will only profit from around $1.2 trillion of investment (71 percent of the total NOC investment) if humanity fails to contain global temperature rise to below 1.5°C, pushing the world toward climate catastrophe.
-
While NOCs are making riskier bets, their debt is rising in some regions. Between 2011 and 2022, the average debt to total asset value of NOCs in sub-Saharan Africa, the Middle East and North Africa, and Latin America rose by a third.
-
Governments’ financial pockets are shrinking. Between 2011 and 2021, the average government debt as a proportion of gross domestic product doubled.
-
Yet many NOCs have not publicly acknowledged the growing risks of the energy transition. They and their governments must examine how they can generate sufficient revenue and energy for citizens without making even riskier bets with public money.
As the energy transition accelerates and government finances deteriorate national oil companies (NOCs) are gambling their countries’ wealth.
As NOCs, along with the rest of the oil industry, expect oil demand to stay high, they will likely invest USD 1.8 trillion in new upstream developments and project expansions over the next 10 years. However, $425 billion of this investment is unlikely to be profitable if global oil demand falls from the current 100 million barrels a day to 55 million barrels a day by 2050, in line with the International Energy Agency’s Announced Pledges Scenario. This is twice the investment NOCs were planning in 2021 before the Russian invasion of Ukraine. In addition, NOCs will likely invest $1.2 trillion in projects that will only break even if humanity fails to keep the global rise in temperatures below 1.5°C, pushing the world toward climate catastrophe.
Even if demand persists, the future is not business-as-usual for NOCs and their governments. Continued burning of fossil fuels will result in further climate damage to nature, societies and economies: a 13 to 29 percent fall in gross domestic product (GDP) for non- OECD countries by mid-century. Nine out of the ten most affected economies have NOCs. Governments should examine how this radically increases uncertainty and challenges the roles of NOCs and the public capital they are investing.
NOCs in China, Saudi Arabia, Russia and Brazil are set to spend the most. In particular, Chinese and other Asia-Pacific NOCs are increasing their investments significantly compared to their plans two years ago. Conversely, NOCs in Latin America, Eurasia and sub-Saharan Africa are reducing their investments.
NOCs in Sub-Saharan Africa, Asia-Pacific and Eurasia are generally the most exposed to risk. A third of all NOCs—including Indonesia’s Pertamina, Nigeria’s NNPC and Mexico’s Pemex—are due to invest more than a third of their investment pipeline in projects that would not break even under the IEA’s Announced Pledges Scenario (APS). A scenario in which governments meet their climate pledges to reduce oil and gas demand. Some smaller NOCs are highly exposed: four-fifths of Uganda’s UNOC and Cameroon’s SNH investment pipelines fail to break even in the APS.
NOC debt is rising in some regions. Between 2011 and 2022, the average debt to total asset value of NOCs in sub-Saharan Africa, the Middle East and North Africa, and Latin America rose by a third.
NOCs’ investment in risky assets represents a large portion of state budgets—with significant consequences for governments’ ability to fund public services in the future. UNOC and NNPC are due to invest an amount equivalent to more than 30 percent of their governments’ annual expenditure in projects that do not break even in the APS. QatarEnergy and Mozambique’s ENH are also betting large amounts relative to their governments’ budgets, but their focus on gas may reduce their risk exposure.
Value of all NOCs’ aggregate “investment pipelines” measured in 2021 and 2023, by scenarios in which they break even


Responsible Change: How Governments Can Address Environmental, Social and Governance Challenges When Petroleum Assets Change Hands

-
As the world moves toward a future beyond oil and gas, petroleum assets will change hands, with different kinds of companies replacing others.
-
Since 2014, around USD 88 billion in assets have moved from publicly listed to private companies. The roles of sub-Saharan African and Latin American companies in their home countries have expanded.
-
Globally, the role of national oil companies (NOCs) is growing. NOCs have acquired around $24 billion in assets from non-NOCs since 2014.
-
The growing role of private and local companies and NOCs potentially gives producer countries greater control over their petroleum sectors, including the pace of an eventual phaseout.
-
However, these companies often have less capacity and fewer transparency, environmental, social and governance commitments than publicly listed international companies. This increases the risk that these companies’ operations will negatively impact the environment and communities, and that they will be unable to pay for decommissioning when production ends.
-
Many assets that sub-Saharan African and Latin American NOCs have acquired appear vulnerable to energy transition risks.
-
Governments should exercise approval rights over asset transfers to ensure buyers have requisite capacity to operate with high standards. They should ensure transparency to allow host communities and the public to better understand transfer impacts and how the government and/or companies will manage them, and strengthen regulations to address key issues arising from transfers including emissions management and reporting, and decommissioning funding.
-
Governments should require NOCs to make adequate disclosures about their acquisitions to ensure NOCs manage risks to the public purse.
As the world journeys towards a future beyond oil and gas, oil and gas assets will continue to change hands, with different kinds of companies filling the gap left behind by others.
There is growing concern that, as international oil companies (IOCs) face pressure to reduce emissions, they are selling upstream petroleum assets, in part, to shift emissions off their books and ostensibly achieve their decarbonization goals. On balance and at a global level, assets are moving from publicly listed to private companies and from companies with higher environmental commitments to those with weaker commitments. The result, according to some evidence, is that these sales do not simply transfer emissions to new parties but may increase them.
At the same time, some national oil companies (NOCs) seek to acquire assets left behind by the departure of IOCs to avoid production decline and ensure domestic energy supply.
This briefing shows how asset transfer trends may differ by region and country, and therefore present different risks and raise different policy considerations for producer country governments. It focuses on the Global South countries and regions in which the Natural Resource Governance Institute (NRGI) works.
NRGI analyzed upstream petroleum asset transfers from 2014 to the first half of 2023, using Rystad data to identify trends globally, at the sub-Saharan African and Latin American regional level, and in NRGI’s countries of focus.
This analysis shows that petroleum assets worldwide have moved primarily from publicly listed to private companies during the period studied. Since the start of 2014, around USD 88 billion in assets have moved from publicly listed to private companies. Both sub-Saharan Africa and Latin America have seen net divestment by publicly listed companies. In sub-Saharan Africa, there has been a transfer of around $23 billion in assets from publicly listed to private companies since the start of 2014, while in Latin America, around $11 billion in assets has moved from publicly listed to private companies.
Mexico’s energy and climate contradictions are laid bare at COP28
COP28 puts spotlight on state oil giants
Oil and gas companies stall on net zero plans
Uganda’s Oil Refinery: Gauging the Government’s Stake

-
Uganda’s planned oil refinery will have several benefits for the country, including for its security of fuel supply and balance of payments.
-
The refinery could be reasonably profitable, generating an internal rate of return of 13 percent in a baseline scenario.
-
The government is planning to take a 40 percent stake but may ultimately pay a higher price for this equity than it expects. Even if it borrows to cover its upfront contribution to costs, it will need to divert around $330 million in present value terms from the national budget for loan repayments in the 2030s.
-
This price will increase if downside risks, such as cost overruns or lower global oil prices, materialize.
-
The government can take several steps to increase interest from other investors, including by reducing the risk of cost overruns, ensuring deregulated product prices continue, and providing less risky forms of state support such as tax incentives. These should reduce the need for the government to take a large stake.
French supermajor Total and Chinese state oil company CNOOC are currently developing Uganda’s first oil project. As part of this, they are constructing the East Africa Crude Oil Pipeline, which will have the capacity to export 216,000 barrels per day (bpd) of oil. The government is also pursuing construction of a refinery that will process 60,000 bpd when built.
The refinery will have several benefits. It should address Uganda’s problem with fuel supply, with current import routes from Kenyan and Tanzanian ports having suffered several disruptions. Fewer petroleum product imports will reduce the country’s foreign exchange needs. The government hopes that the refinery will also stimulate the birth of a petrochemical industry and generate thousands of jobs.
The key question for the government now is when and how the planned refinery will go ahead, including in relation to its planned equity stake. The government canceled its agreement with the Albertine Graben Refinery Consortium (AGRC), the companies selected to construct and operate the refinery, in June 2023 after AGRC failed to secure sufficient financing within the agreed timeframe. The government has been planning to take an equity stake of up to 40 percent in the refinery through the Uganda National Oil Company (UNOC). But the challenges with AGRC could encourage the government to take an even larger stake to ensure the project proceeds.
There is limited clarity on the price that the government might ultimately pay for its equity stake. To provide further clarity and thereby inform government decision-making, this paper's authors have analyzed the refinery’s economics and the implications for the government stake.
The authors’ modeling suggests that the refinery could be reasonably profitable. With their baseline assumptions, it generates an internal rate of return (IRR) of 13 percent.
With a construction cost of $4.5 billion and assuming debt financing of 70 percent, a government stake of 40 percent requires the government to contribute around $540 million. This is equivalent to about $440 million in present value terms (assuming a real discount rate of 8 percent). Given budgetary constraints, the authors expect that the government will borrow this money to avoid this upfront cost.
But borrowing is not a silver bullet. While UNOC ultimately makes a profit over the lifetime of the refinery in the authors' baseline, the government needs to divert around $330 million in present value terms from the budget to contribute to loan repayments in the 2030s.
The price that the government ultimately pays for a 40 percent stake will be impacted by a range of factors and uncertainties that affect the profitability of refineries. The authors analyzed five factors that will affect the profitability of the Ugandan refinery: construction cost, feedstock volume, global oil price, product prices and regional exports.
The government will pay a very different price to what it expected even if only some of these downside risks materialize. Taking a large equity stake could therefore generate substantial challenges for Uganda.
Given that the refinery will have considerable benefits for Ugandans, the government may decide this is a risk worth taking, and a price worth paying. However, the government may not need to expose the country to this amount of risk. It is unclear whether the failure of AGRC to raise sufficient financing relates to the refinery’s profitability or other reasons, particularly given the refinery is profitable in the authors' baseline. If the government can establish and address the reasons for AGRC’s fundraising failure, other investors may still be willing and able to provide most, if not all, the investment.
In this paper the authors identify several steps that the government can take to increase interest from other investors and thereby reduce the risk that the refinery hinders rather than helps Uganda’s development.
National Oil Companies Betting $1.2 Trillion of Public Money On Climate Catastrophe

State-run oil companies plan to spend $1.2 trillion on oil and gas projects that won’t turn a profit if humanity manages to meet the International Energy Agency’s “net zero” climate change scenario, new research shows.
The massive sum reflects an increase in potentially unprofitable hydrocarbon spending by national oil companies, when compared to similar calculations made two years ago by the Natural Resource Governance Institute. NRGI’s updated analysis, Riskier Bets, Smaller Pockets: How National Oil Companies Are Spending Public Money Amid the Energy Transition, out today, finds that while many oil-producing countries plan to invest more on extraction, they have also become more indebted.
“This concurrence of rising debt and increased willingness to spend on fossil fuel expansion is a perfect storm for both climate and economic disaster,” said David Manley, one of the report’s authors. “Either these investments turn a profit, or we manage to halt warming fast enough to avoid catastrophic and irreversible impacts. It’s one or the other. Citizens in poor countries cannot afford even worse climate impacts, and their governments cannot afford to bail out state oil producers that make bets on risky fossil fuel projects.”
Even under climate change scenarios less stringent than “net zero,” vast amounts of public funds are still at risk, the authors found. In the IEA’s “announced pledges” scenario, in which demand for oil falls to 55 million barrels a day, $425 billion of state companies’ planned investment over the next decade will be unprofitable.
“These are huge sums of money that belong to citizens, often in countries where inequality and poverty persist,” said Suneeta Kaimal, president and CEO of NRGI. “Now more than ever governments should invest seriously in plans to diversify their economies away from dependence on oil and gas production. Yet over the last two years we’ve seen national oil companies double the riskiest portions of their portfolios with plans to invest in high-cost projects.”
In a second report published today, Facing the Future: What National Oil Companies Say About the Energy Transition, NRGI reveals that only nine out of 21 NOCs analyzed have acknowledged the risks of the energy transition, with a mere four implementing transition risk assessments and five outlining concrete strategies to mitigate these risks. None of the analyzed NOCs have published “just transition plans” that would detail how they intend to support workers and communities affected by evolutions in the energy sector.
“While NOCs like Brazil’s Petrobras and Colombia’s Ecopetrol have some good practices that others could follow, most NOCs we analyzed are covered in red flags,” said Andrea Furnaro, one of the report’s authors. “National oil companies must urgently and publicly acknowledge the risks, conduct thorough risk assessments, and implement effective mitigation plans to protect public capital at risk in the context of the energy transition. Transition risk disclosure is essential to enable citizens, investors and policymakers to scrutinize NOCs’ decisions.”
NRGI’s reports, published two days before the COP28 climate conference in Dubai, build on recent findings by UNEP and climate think tanks that governments in oil-producing countries and NOCs are investing far too much public revenue in oil and gas. This overinvestment will result in the production of more than double the amount of fossil fuels than would be consistent to limiting global warming to 1.5 degrees above pre-industrial levels.
“Even as governments gather to take stock of global progress this week, they still gravely underestimate the role that national oil companies must play in reaching the Paris Agreement's objectives,” said NRGI’s Patrick Heller, an author of Riskier Bets, Smaller Pockets. “Our research shows how urgent it is for governments at COP28 to face up to the reality of national oil company investment plans. They should send a strong signal that the future demands a shift away from oil and gas that is rapid as well as equitable, including with concrete commitments to support transition in low-income countries.”
For more information
Lee Bailey, Communications Director | lbailey@resourcegovernance.org | +44 (0)7823 442 954
Notes to editors
- This research will be discussed at two upcoming events open to the media:
- Underlying data as well as editable formats of the reports’ charts and graphs and data are available upon request
Beyond the Peak: Planning for Just Transitions in Oil and Gas (COP28 Blue Zone Event)

Despite mounting evidence that the expansion of oil and gas production is incompatible with a Paris Agreement 1.5°C-aligned pathway, many countries, national and international companies, and financial institutions persist in pursuing such plans. Current oil and gas production plans from major producers would already overshoot the 1.5°C target by 110 percent in 2030, according to the 2023 Production Gap Report.
Yet, the transition away from fossil fuels including oil and gas is accelerating, driven by a combination of environmental, social, economic and ethical considerations. Fair, inclusive and managed transitions can not only address the unequal distribution of costs and benefits but serve as catalysts for ambition and implementation. Therefore, a broader understanding of the equity implications of the transition away from oil and gas is crucial to advance this global mandate.
Speakers:
- Suneeta Kaimal, President and CEO, Natural Resource Governance Institute (moderator)
- Javier Campillo, Vice-Minister of Energy, Colombia
- Adriana Chavarría-Flores, Program and Impact Manager, Climate Strategies
- David Manley, Lead Economic Analyst for Energy Transition, Natural Resource Governance Institute
- Hauwa Mustapha, Climate Coordinator, Nigerian Labour Congress, & ITUC Africa
- David Waskow, Director, International Climate Initiative, World Resources Institute
Featuring NRGI's
Suneeta Kaimal
President and Chief Executive Officer, NRGI Governing Board ex officio

National Oil Companies in the Energy Transition

Riskier Bets, Smaller Pockets quantifies the amount of public finance that NOCs are putting at risk by investing in high-cost projects that won’t break even if the world meets targeted warming limits; it also considers the implications of growing debt among many oil-producing countries.
Facing the Future: What National Oil Companies Say About the Energy Transition is an analysis of NOCs’ public statements acknowledging and mitigating risks that transition poses to their business models.
In this one-hour online event, the authors presented the key findings of these research products, followed by a conversation with two guest discussants on how some of the central issues surrounding the energy transition, including its risks and opportunities, manifest in the specific cases of GNPC in Ghana and Pemex in Mexico.
Featuring:
- Kwame Baah-Nuakoh, Ghana National Petroleum Corporation
- Andrea Furnaro, NRGI
- Patrick Heller, NRGI
- David Manley, NRGI
- Ana Lilia Moreno, Mexico Evalúa
Featuring NRGI's
Press Conference: National Oil Companies and Energy Transition Challenges (COP28 Blue Zone Event)

As public entities, national oil companies (or NOCs) are owned by the citizens of oil-producing countries, many of which face persistent poverty and high inequality. At this press conference three experts spoke on national oil companies, climate and energy transition for insights on NOCs and what is at stake at COP28.
Topics and speakers
Risky bets and public funds. Despite the imperative to transition beyond fossil fuels, NOCs are planning $1.8 trillion on oil and gas developments and expansions over the next 10 years. Seventy-one percent of these investments will only turn a profit if humanity fails to meet the 1.5 C target. A quarter of the total NOC investment will be unprofitable if oil demand falls to 55 million barrels a day, which is in line with the International Energy Agency’s Announced Pledges Scenario.
NRGI's Denis Gyeyir briefed on these and other findings from Riskier Bets, Smaller Pockets: How National Oil Companies are Spending Public Money Amid the Energy Transition, a new research publication from the Natural Resource Governance Institute (NRGI). Questions on another recent NRGI report, Facing the Future: What National Oil Companies Say About the Energy Transition, were also welcome.
Finance and investors. NOCs face increasing uncertainties due to changing energy systems. But financial actors’ approaches are currently not aligned with the need to mainstream climate considerations into NOC business models.
IISD's Natalie Jones shared insights on how financial actors can support NOCs’ just and ambitious low-carbon transition, based on new analysis by the International Institute for Sustainable Development (IISD), the World Benchmarking Alliance, and the University of California Santa Barbara.
Just transition. Just transition for oil and gas producers is a relatively new area, particularly their role in helping their countries achieve a just transition – in terms of economic diversification, jobs, communities, revenue management, contracting and governance.
Glada Lahn of Chatham House shared early findings from new research on what just transition means for middle-income oil and gas producing countries, focusing on the cases of Colombia and Nigeria. This research is being led by Chatham House, the World Resources Institute (WRI), and national researchers in Colombia and Nigeria.
This event was livestreamed on the UNFCCC website.
To arrange interviews, contact:
- Lee Bailey, in London, at lbailey@resourcegovernance.org, +44 (0)7447 560488
- Gabriela Flores, in Dubai, at gflores@resourcegovernance.org, +44 (0)7931 924934
Featuring NRGI's
Gabriela Flores Zavala
Communications Strategy Consultant


